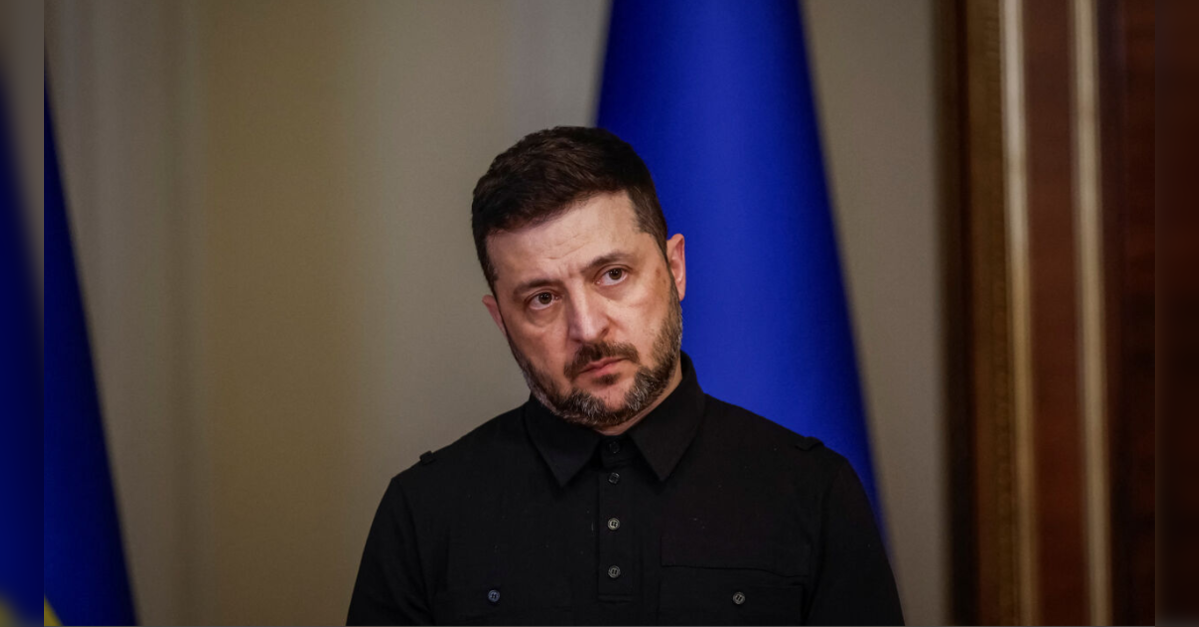
The geopolitical landscape continues to exert profound influence over global energy markets, as evidenced by recent calls for intensified sanctions against Russia. Ukrainian President Volodymyr Zelensky has lauded the “very important” new US and European Union energy restrictions, which include measures against major Russian oil companies and an EU ban on Russian liquefied natural gas (LNG) imports. His persistent advocacy for “more pressure” underscores a belief that further economic isolation is crucial for achieving a ceasefire. This latest round of sanctions, initially announced in October 2025, continues to ripple through the market, forcing investors to re-evaluate supply chains, pricing dynamics, and the broader risk profile of the global energy sector as we navigate the complexities of April 2026.
The Evolving Impact of Sanctions on Global Energy Supply
The strategic implementation of energy sanctions against Russia, particularly since the full-scale invasion commenced in February 2022, has fundamentally reshaped global energy flows. The latest US measures targeting prominent Russian oil entities and the EU’s decisive ban on Russian LNG imports are designed to constrict Moscow’s revenue streams further. While such actions aim to achieve political objectives, their economic ramifications for the global energy complex are undeniable. These restrictions compel traditional buyers to seek alternative sources, often at higher logistical costs, and force Russia to pivot its exports to new markets, frequently at discounted rates. The long-term effect is a fragmentation of the global energy market, creating inefficiencies and driving a persistent underlying tension that influences commodity pricing and infrastructure investment decisions. Investors must carefully assess how these evolving supply corridors impact regional energy security and global trade balances.
Navigating Current Market Volatility Amid Geopolitical Headwinds
The interplay of geopolitical pressures and fundamental market forces is clearly reflected in recent price movements. As of today, Brent Crude trades at $90.38, representing a significant 9.07% decline within the trading day, with prices oscillating between $86.08 and $98.97. Similarly, WTI Crude has seen considerable volatility, currently priced at $82.59, down 9.41% and ranging from $78.97 to $90.34 over the same period. This recent downward trend stands in stark contrast to the broader two-week trajectory, where Brent fell from $112.78 on March 30 to its current level, marking a substantial 19.9% depreciation. Gasoline prices have also followed suit, now at $2.93, a 5.18% drop today. This heightened volatility underscores the market’s sensitivity to both perceived supply disruptions from sanctions and potential demand headwinds stemming from broader economic concerns. For investors, understanding the drivers behind these sharp movements – whether it’s a temporary oversupply perception, a reaction to global economic indicators, or continued geopolitical uncertainty – is paramount for risk management and strategic positioning.
Investor Focus: Forward-Looking Catalysts and Market Sentiment
Our proprietary reader intent data reveals a keen investor focus on future price trajectories and the factors that will shape them. Questions such as “what do you predict the price of oil per barrel will be by end of 2026?” are consistently among the most frequent inquiries, highlighting a desire for long-term clarity in an uncertain environment. This forward-looking perspective naturally aligns with a close watch on upcoming calendar events. The immediate future holds critical data points for the market, beginning with the OPEC+ Joint Ministerial Monitoring Committee (JMMC) meeting this Sunday, April 19, followed by the full OPEC+ Ministerial Meeting on Monday, April 20. These gatherings are pivotal, particularly as investors frequently inquire about “OPEC+ current production quotas.” Any adjustments to output policy, or even strong signals regarding future intentions, could significantly impact supply expectations and price stability, especially given the current market volatility and the ongoing pressure from Russian sanctions. Further insights into supply and demand dynamics will come from the API Weekly Crude Inventory report on April 21 and the EIA Weekly Petroleum Status Report on April 22, providing crucial snapshots of US stockpiles. The Baker Hughes Rig Count on April 24 will offer a gauge of future production capacity. Beyond macro trends, investors are also examining how individual energy companies are positioned to navigate these complex conditions, scrutinizing their resilience to geopolitical shocks and their ability to adapt to evolving market structures.
The Strategic Calculus of Deeper Sanctions and Geopolitical Objectives
Zelensky’s unwavering call for “more pressure” on Russia through additional sanctions highlights the continued belief that economic measures are an effective tool to influence geopolitical outcomes. The latest EU ban on Russian LNG represents a significant expansion of the sanctions regime, moving beyond crude oil to target another critical energy export. While sanctions undeniably inflict economic pain on the target nation, their effectiveness in altering political behavior is a complex and often debated topic. For investors, the crucial consideration is the potential for escalation and the subsequent impact on global energy prices and supply security. Deeper sanctions could further tighten global energy markets, potentially leading to higher prices, but they also risk retaliatory measures or unintended consequences that could disrupt supply chains for other commodities. Understanding the delicate balance between geopolitical objectives and market stability is critical for anticipating future energy market movements. The ongoing geopolitical tension, coupled with the strategic responses from major energy-consuming nations, ensures that energy markets will remain highly sensitive to political developments.
Conclusion: Navigating a Geopolitically Charged Energy Landscape
The global energy market remains deeply intertwined with geopolitical developments, particularly the ongoing conflict and the international community’s response through sanctions. While President Zelensky advocates for an intensified economic squeeze on Russia, the market continues to react with significant volatility, influenced by both the immediate implications of these measures and broader economic uncertainties. Investors must remain vigilant, closely monitoring not only the shifting geopolitical sands and the efficacy of sanctions but also key fundamental data points, including OPEC+ decisions and inventory reports. The pursuit of deeper sanctions will continue to test the resilience of global supply chains and shape the profitability landscape for energy companies. Success in this environment will hinge on a nuanced understanding of these complex interdependencies and an agile investment strategy.


