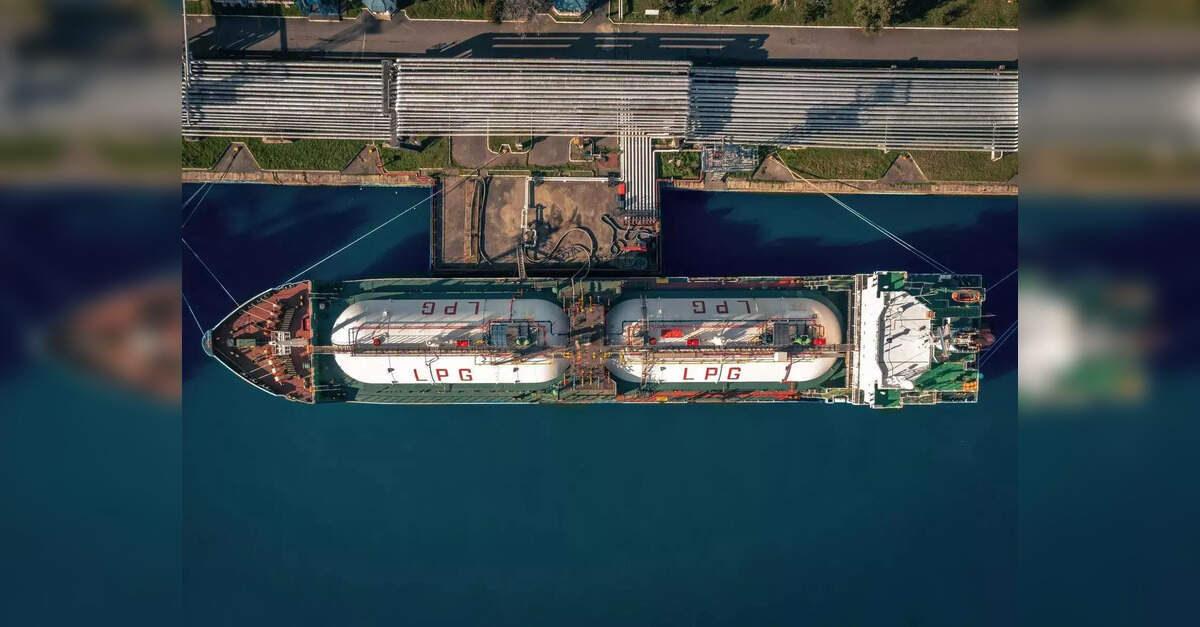
India’s colossal energy appetite is a perennial focus for global investors, and a significant pivot is underway within its liquefied petroleum gas (LPG) sector. Driven by evolving geopolitical dynamics and a strategic reorientation of trade partnerships, India is actively pursuing its first long-term supply agreements for LPG from the United States. This move represents a foundational shift for both nations, offering a robust new market for burgeoning US energy exports and a diversified, secure supply for India’s massive domestic needs. For energy investors, this burgeoning relationship signals a compelling long-term demand story, particularly for US midstream infrastructure and LPG export capabilities, against a backdrop of complex global commodity markets.
Geopolitical Realignment Reshaping Global LPG Flows
The intricate dance of international trade policies, particularly the escalating friction between the US and China, is creating a tangible remapping of global commodity flows. LPG, a critical fuel for cooking and a vital petrochemical feedstock, has found itself squarely in the crosshairs of these geopolitical tensions. With China increasingly facing tariffs on US goods, including LPG, and consequently shifting its sourcing towards Middle Eastern suppliers or seeking discounted US cargoes, a significant volume of American LPG is now seeking alternative destinations. Enter India. The nation’s state-owned oil companies—responsible for supplying LPG to over 331 million domestic consumers—have initiated a tender to secure up to three very-large gas carriers (VLGCs) of US-sourced LPG monthly, commencing in 2026. This is not merely a spot market transaction; it marks India’s inaugural pursuit of a long-term contractual arrangement for US LPG, a strategic departure from its historical reliance on suppliers like Saudi Arabia. This proactive engagement is further bolstered by India’s broader diplomatic efforts to enhance energy cooperation with Washington, aiming to alleviate the 50% tariffs imposed on certain Indian goods.
India’s Structural Demand & The Investor Lens
India’s immense population and rapidly expanding middle class underpin a persistent and growing demand for energy, making its LPG market particularly attractive to investors. With over 60% of its cooking fuel imported, the imperative for secure, diversified supply chains is paramount. This long-term tender from Indian Oil Corp., Bharat Petroleum Corp., and Hindustan Petroleum Corp. is a direct response to this structural demand, projecting a predictable and substantial revenue stream for US producers and exporters well into the future. Our first-party data reveals that investors are keenly focused on long-term market trajectories; a frequent inquiry we’ve observed this week asks, “what do you predict the price of oil per barrel will be by end of 2026?” While this query targets crude, it underscores a broader investor desire to understand fundamental demand drivers that can stabilize and support energy prices over extended periods. The consistent, large-scale demand from India for US LPG provides precisely this type of underlying market support, de-risking investments in the US LPG value chain from production to export terminals and shipping.
Navigating Volatility: Market Prices and Upcoming Catalysts
The broader energy market currently presents a dynamic backdrop to this burgeoning US-India LPG trade. Our live market snapshot indicates that Brent Crude is trading at $90.38 as of today, representing a notable 9.07% decline within the trading day, with prices having retreated from $112.78 just a few weeks ago. WTI Crude similarly reflects this bearish sentiment, currently at $82.59, down 9.41%. While LPG pricing is influenced by NGLs rather than directly by crude, these benchmarks signal the overall sentiment and cost environment for hydrocarbon production. This volatility necessitates a sharp focus on competitive dynamics. Middle Eastern LPG suppliers, including Saudi Aramco, are actively responding to this new competitive landscape by adjusting pricing strategies and integrating Asian market rates more strongly into their contract terms. This ensures that US LPG exports will need to remain price-competitive to fully capitalize on India’s demand.
Looking ahead, several critical events will shape the near-term outlook. The upcoming OPEC+ Ministerial Meeting on April 19th is a pivotal moment, with our readers frequently asking, “What are OPEC+ current production quotas?” Decisions from this meeting will directly impact global crude supply and, by extension, the economics of associated gas and NGL production in the US. Furthermore, the API Weekly Crude Inventory (April 21st, April 28th) and EIA Weekly Petroleum Status Report (April 22nd, April 29th) will offer crucial insights into US petroleum stockpiles, refining activity, and NGL inventories, providing leading indicators for domestic LPG supply and pricing power. The Baker Hughes Rig Count on April 24th and May 1st will further inform our understanding of future US shale production trends, directly impacting the availability of feedstocks for LPG.
Strategic Implications for US Energy Export Infrastructure
This strategic shift by India towards long-term US LPG contracts carries profound implications for the American energy export infrastructure. It underpins the necessity for continued investment in natural gas liquids (NGL) fractionation capacity, storage facilities, and crucially, expanded export terminal capabilities along the US Gulf Coast. With India requiring a consistent flow of up to three VLGCs per month from 2026, this commitment provides a stable baseline demand that mitigates some of the cyclical risks often associated with commodity markets. For investors eyeing the midstream sector, this represents a significant de-risking factor, justifying capital allocation towards projects that facilitate the liquefaction and export of propane and butane. The move solidifies the US position not merely as a swing producer of crude but as a reliable, long-term supplier across the hydrocarbon spectrum, diversifying its export portfolio beyond traditional crude and LNG. This strengthens bilateral energy ties and provides a strategic hedge against future geopolitical shifts, ensuring that US energy assets remain globally competitive and strategically vital.


