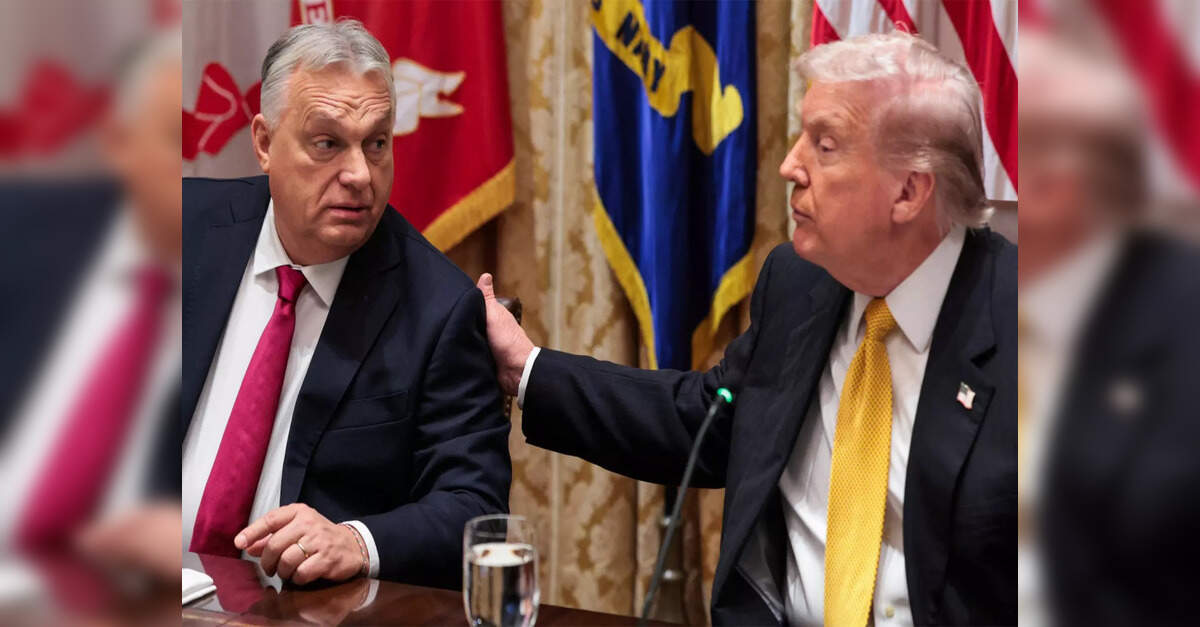
The geopolitical landscape of global energy markets remains incredibly volatile, with recent developments highlighting the complex interplay between foreign policy, energy security, and crude supply dynamics. A significant point of discussion for investors emerged with United States President Donald Trump’s indication that he is reviewing Hungary’s request for an exemption from sanctions on Russian oil. This potential policy shift, aimed at assisting a landlocked European nation in securing vital energy supplies, could have ripple effects across the market, challenging the integrity of existing sanctions and influencing broader investor sentiment towards energy commodities. For astute investors, understanding the nuances of such policy considerations, alongside fundamental market data and upcoming events, is paramount for navigating the choppy waters of the oil and gas sector.
Geopolitical Maneuvering and European Energy Security
The prospect of the U.S. granting Hungary an exemption from Russian oil sanctions introduces a fascinating new variable into the ongoing energy security debate in Europe. Hungarian Prime Minister Viktor Orban has consistently voiced concerns over the impact of strict energy sanctions on his nation, which relies heavily on Russian oil and gas delivered via pipelines. His argument centers on Hungary’s geographical disadvantage, lacking coastal access and thus ports, making alternative energy acquisition particularly challenging and costly. The U.S. administration, having imposed significant sanctions on Russian state-run oil giants Rosneft and Lukoil in October, now faces a delicate balancing act. While the original sanctions aimed to pressure Moscow following its withdrawal from Ukraine peace talks, a carve-out for Hungary would underscore the immense difficulties some European nations face in decoupling from Russian energy. Investors should watch closely how any such exemption is framed and whether it sets a precedent or remains an isolated case, as it could signal a potential softening or increased flexibility in the broader Western sanctions regime against Russia, thereby influencing perceptions of global oil supply.
Current Market Dynamics Amidst Policy Uncertainty
The oil market is currently in a state of flux, reacting to a multitude of factors, including geopolitical shifts and evolving supply-demand narratives. As of today, Brent Crude trades at $90.38 per barrel, marking a notable decline of 9.07% within the day’s trading range of $86.08 to $98.97. Similarly, WTI Crude stands at $82.59, down 9.41%, having fluctuated between $78.97 and $90.34. This significant intraday volatility comes against a backdrop of a pronounced downward trend for Brent, which has shed $22.40, or 19.9%, from its $112.78 perch on March 30. Gasoline prices have also seen a dip, currently at $2.93, a 5.18% decrease. While specific reasons for today’s sharp decline are complex, the discussion around potential sanction relief, even for a single nation, can contribute to a perception of loosened supply constraints, adding to downward pressure, especially when combined with other market concerns. Investors must recognize that even small geopolitical signals can amplify existing market sentiment, particularly when liquidity is high or uncertainty abounds.
Investor Queries and the Future Price Trajectory
Our proprietary data on investor intent reveals a clear focus on the future trajectory of oil prices and the policies that underpin global supply. A recurring question among our readers this week is, “What do you predict the price of oil per barrel will be by end of 2026?” This highlights the deep uncertainty surrounding long-term market fundamentals. Another key query revolves around OPEC+ current production quotas, underscoring the critical role of cartel policy in managing global supply. The potential for the U.S. to grant sanction relief to Hungary directly impacts these investor concerns. Any adjustment to the sanctions framework, however localized, adds another layer of complexity to supply forecasts. If a precedent were to be set, or if it signals a broader re-evaluation of energy sanctions, it could meaningfully alter the supply-side equation, making price predictions even more challenging. Investors are essentially asking how geopolitical flexibility will translate into barrels on the market, directly influencing their portfolio strategies and risk assessments for the coming years.
Navigating Upcoming Events and Forward Outlook
For investors positioning themselves in the current environment, the coming weeks are packed with critical events that will further shape the oil market’s direction. The immediate focus will be on the OPEC+ Joint Ministerial Monitoring Committee (JMMC) Meeting on April 19, followed swiftly by the full OPEC+ Ministerial Meeting on April 20. These gatherings are pivotal, as member nations will review current market conditions and potentially adjust production quotas. Any discussion of increased output, or conversely, a decision to maintain existing cuts, will significantly impact crude prices. Against this backdrop, the possibility of the U.S. granting sanction relief to Hungary, even if minor in terms of overall supply, introduces a variable that OPEC+ leaders might consider in their deliberations, potentially influencing their perception of global supply stability. Furthermore, regular insights into U.S. demand and production will come from the API Weekly Crude Inventory reports on April 21 and April 28, and the EIA Weekly Petroleum Status Reports on April 22 and April 29. These reports will provide crucial data points on inventory levels and refinery activity, offering a clearer picture of domestic supply and demand dynamics. Investors should also monitor the Baker Hughes Rig Count on April 24 and May 1 for signals on future U.S. production capacity. The convergence of these fundamental data releases with ongoing geopolitical developments, such as the potential Hungarian exemption, creates a highly dynamic environment that demands constant vigilance and agile investment strategies.


