The Power of Siberia 2: Reshaping Global Gas Flows and Investor Horizons
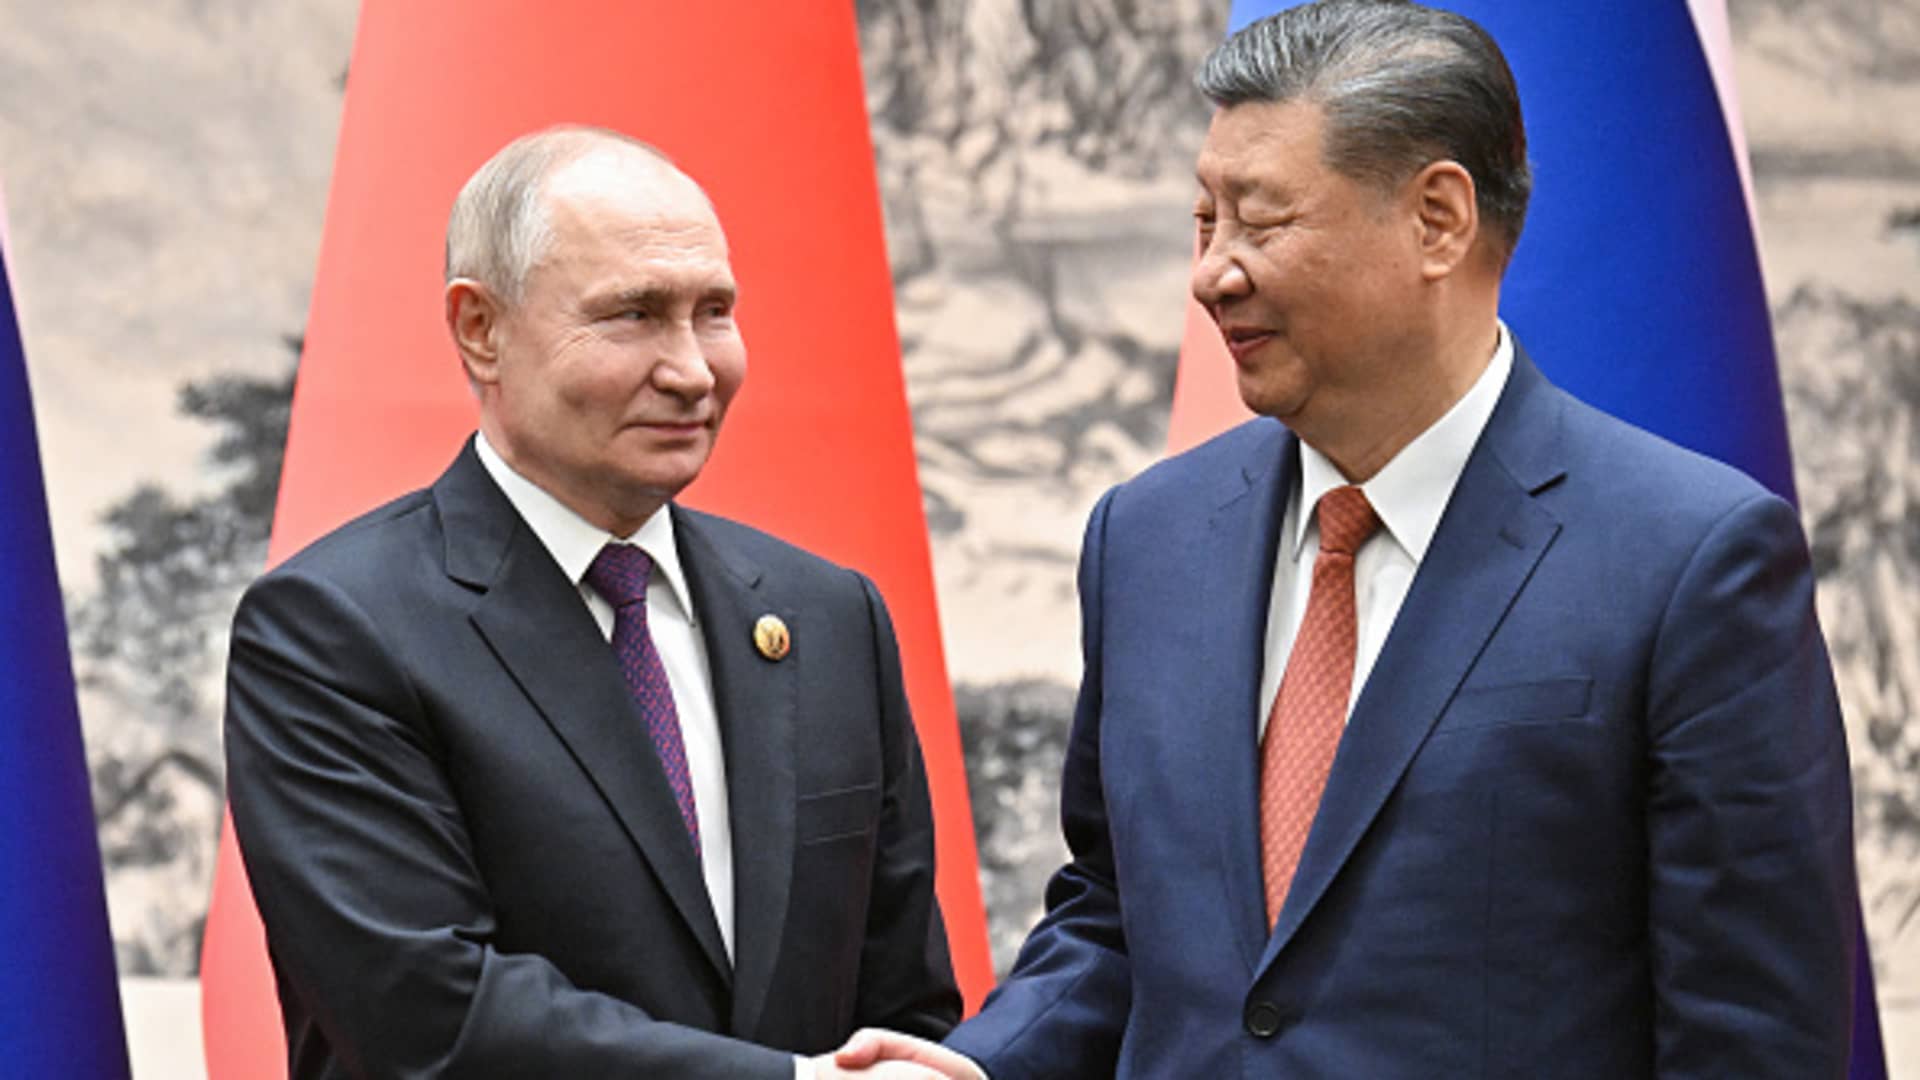
A landmark agreement between Russia and China to construct the Power of Siberia 2 gas pipeline is poised to fundamentally alter the global energy landscape, deepening commercial ties between the two nations and sending a clear geopolitical signal. This legally binding deal, confirmed by Gazprom CEO Alexei Miller following talks between Presidents Putin and Xi Jinping, will enable the supply of 50 billion cubic meters (bcm) of gas per year from Russia’s West Siberian reserves to northern China, traversing eastern Mongolia, for a period of 30 years. For investors in the oil and gas sector, this move isn’t just about natural gas; it represents a significant long-term strategic pivot that could influence everything from crude oil prices to the profitability of major energy players globally.
A Strategic Pivot: Russia’s Eastern Gas Gambit
The Power of Siberia 2 pipeline marks a critical inflection point for Russia’s energy strategy, accelerating its pivot towards Asian markets amidst a sustained decline in gas exports to Europe. Since early 2022, punitive Western sanctions and a concerted effort by the European Union and the U.S. to reduce dependency on Russian fossil fuels have drastically curtailed Moscow’s primary gas revenue stream. The EU, for example, has targeted an end to Russian gas and oil imports by 2027. This new agreement provides Russia with a robust, long-term alternative customer for its vast gas reserves, ensuring a significant portion of its production has a guaranteed market. For China, the pipeline enhances its energy security through diversification, tapping into a vast overland supply route that bypasses maritime chokepoints. While the specific gas price will be agreed upon separately, the sheer scale and duration of the deal underscore a powerful, coordinated effort to establish a new multipolar energy order, with profound implications for global trade flows and geopolitical alliances.
Navigating Volatility: Market Snapshot and the Road Ahead
Against this backdrop of strategic realignment, energy markets are exhibiting significant volatility. As of today, Brent Crude is trading at $90.38, reflecting a sharp decline of 9.07% within the day, having ranged from $86.08 to $98.97. WTI Crude mirrors this trend, currently at $82.59, down 9.41% today, with an intra-day range of $78.97 to $90.34. Gasoline prices have also seen a notable dip, standing at $2.93, a 5.18% decrease. This daily slump follows a broader trend; our proprietary data shows Brent Crude has shed 18.5% over the past 14 days, falling from $112.78 on March 30 to $91.87 just yesterday. While the Power of Siberia 2 deal primarily impacts natural gas markets, this geopolitical shift contributes to the overall risk premium and sentiment in the broader energy complex. Investors need to consider how a recalibration of global gas supply lines might indirectly affect crude oil demand dynamics and the competitive landscape for other energy sources, particularly LNG, as Russian gas finds a new, massive outlet.
Investor Focus: OPEC+, Inventories, and Price Trajectories
Our first-party reader intent data highlights that investors are acutely focused on the future trajectory of oil prices and the operational specifics of OPEC+ production quotas this week. The significant recent drop in crude prices places immediate scrutiny on the upcoming OPEC+ meetings. The Joint Ministerial Monitoring Committee (JMMC) convenes tomorrow, April 18th, followed by the full OPEC+ Ministerial Meeting on April 19th. These meetings are critical; market participants will be watching closely for any signals regarding production adjustments in response to current price weakness. Should OPEC+ decide to maintain current quotas, or even consider further cuts, it could provide a floor for prices. Conversely, inaction might exacerbate downward pressure. Beyond OPEC+, the market will digest the API Weekly Crude Inventory report on April 21st, followed by the EIA Weekly Petroleum Status Report on April 22nd, both crucial for assessing short-term supply and demand balances. Further inventory reports are scheduled for April 28th and 29th, alongside the Baker Hughes Rig Count on April 24th and May 1st, which offer insights into future production capacity. These near-term events, combined with the long-term strategic implications of the Russia-China gas deal, are the primary drivers influencing investor predictions for oil prices by the end of 2026, shaping strategies for navigating a complex and increasingly multipolar energy market.

