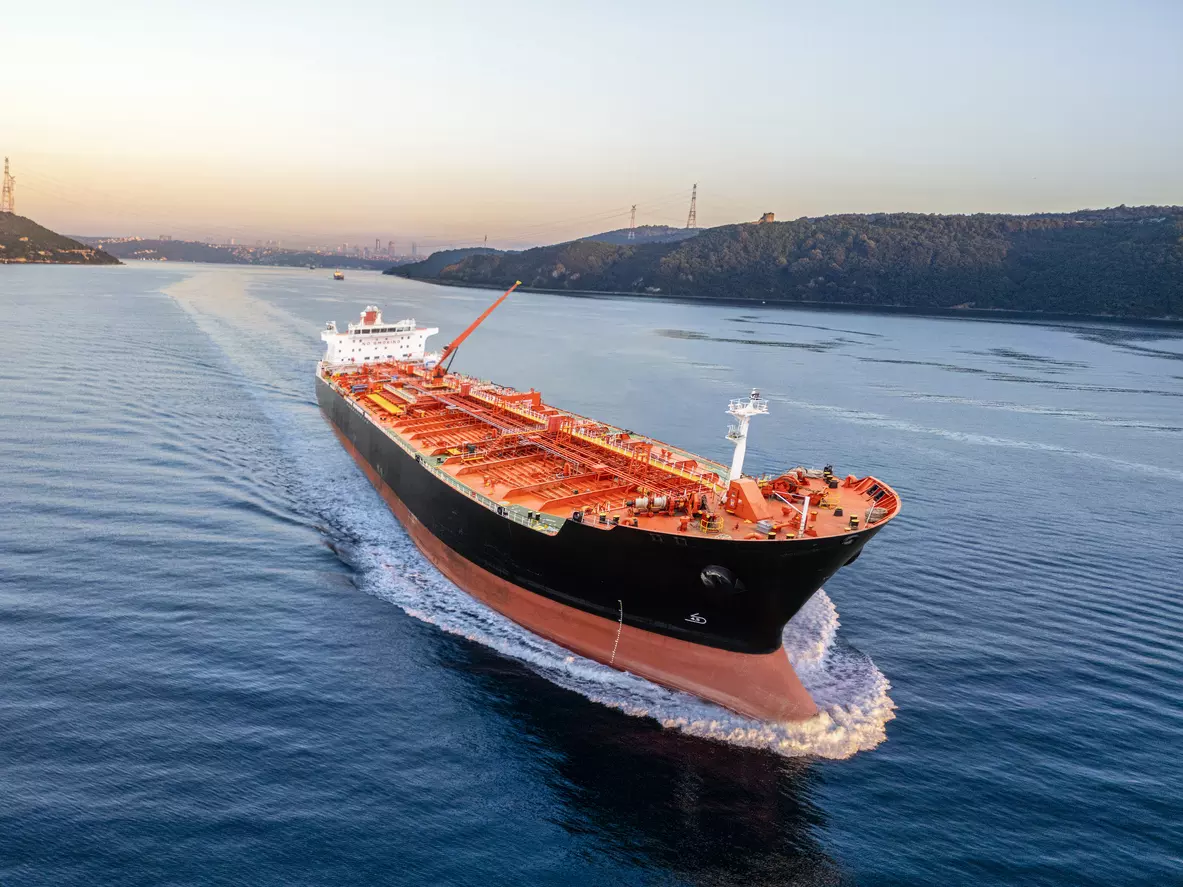
The recent decision by India’s state-owned oil marketing companies (OMCs) to slash their projected ship orders by nearly half, from an initial 112 vessels to just 59 over the next 10-15 years, sends a significant signal through the global oil and gas investment landscape. This isn’t merely a localized procurement adjustment; it represents a tangible shift in capital expenditure strategy, reflecting evolving demand projections, a drive for logistical efficiency, and perhaps a cautious outlook on long-term energy markets. For investors, this move by major national oil companies, which initially earmarked an estimated ₹85,400 crores for these vessels, underscores a broader trend of capital discipline that warrants close examination.
Capex Contraction: A Bellwether for Global O&G Investment
The reduction in ship orders from 112 to 59 vessels, a decision made during a review meeting in October, signifies a substantial recalibration of future infrastructure investment by key players like Indian Oil Corporation Ltd, Bharat Petroleum Corporation Ltd, Hindustan Petroleum Corporation Ltd, and Oil and Natural Gas Corporation Ltd. While the total number of vessels has decreased, the revised plan emphasizes larger vessel types such as Very Large Crude Carriers (VLCCs), Suezmax, and Aframax tankers, alongside Very Large Gas Carriers (VLGCs) and LNG carriers. This strategic pivot suggests a move away from numerous smaller Long Range/Medium Range (LR/MR) tankers towards fewer, but significantly larger, vessels (ranging from 0.8 lakhs to 3.2 lakhs Deadweight Tons). This optimization could imply a consolidation of shipping routes, a belief in sustained long-haul crude and gas movements, or an effort to reduce operational costs per barrel/cargo. From an investment perspective, this reduction in overall newbuild demand, especially from state-backed entities that typically have long-term horizons, suggests a more conservative capital allocation environment within the global energy sector.
Navigating Market Volatility: Investor Concerns and Current Prices
The cautious approach demonstrated by the Indian OMCs comes at a time of considerable volatility in global energy markets. As of today, Brent Crude trades at $90.38, marking a significant 9.07% decline within a single trading session, with the day’s range spanning from $86.08 to $98.97. Similarly, WTI Crude stands at $82.59, down 9.41% for the day. This immediate downturn is part of a broader trend our proprietary data indicates, with Brent having shed nearly 20% from $112.78 just a few weeks ago on March 30th. Such sharp price movements undoubtedly factor into long-term investment decisions. Our reader intent data highlights a pervasive concern among investors regarding future price stability, with many frequently asking, “What do you predict the price of oil per barrel will be by the end of 2026?” The OMCs’ decision to scale back vessel orders, even while upgrading vessel size, could be interpreted as an acknowledgment of this price uncertainty, signaling an intention to operate more leanly and efficiently in a potentially lower or more volatile price environment. This proactive capital discipline, therefore, offers a tangible data point for investors attempting to model future oil price trajectories and industry profitability.
Strategic Vessel Upgrades and Global Supply Chain Implications
The revised shipping strategy, prioritizing larger vessels like VLCCs, Suezmax, and Aframax tankers, has profound implications beyond just the quantity of ships. These larger vessels are typically used for long-haul transportation of crude oil and refined products, suggesting a long-term commitment to global trade routes and the importance of economies of scale in logistics. While this shift aims for greater efficiency, it also highlights a significant technological challenge for India’s local shipbuilders, who have historically lacked the expertise and infrastructure to construct such specialized, large-capacity vessels. Their plea for higher financial aid under the Shipbuilding Financial Assistance scheme for these types of ships, which was not agreed upon by the government, underscores the competitive global landscape. India currently holds a paltry 0.07% share in global shipbuilding and less than 1% in global shipping tonnage. This reliance on larger, more complex vessels means that while the overall order book is smaller, the technological sophistication required for new builds is higher, potentially redirecting orders to more established global shipyards capable of handling these advanced specifications. Investors should view this as a signal that OMCs are optimizing their supply chains for global reach and cost-effectiveness, rather than solely supporting local industrial development.
Forward-Looking Analysis: Upcoming Events and Market Repercussions
The implications of this capex slowdown extend to upcoming market catalysts. This cautious posture from significant state-owned entities in a major consuming nation like India could certainly influence global supply-demand dynamics and sentiment, especially as key industry meetings approach. For instance, the OPEC+ Joint Ministerial Monitoring Committee (JMMC) Meeting on April 19th and the subsequent OPEC+ Ministerial Meeting on April 20th will be critical. Our proprietary data shows that investors are actively asking, “What are OPEC+ current production quotas?” A perceived softening in long-term demand growth, as suggested by reduced shipping capacity expansion, could exert pressure on OPEC+ members to consider their production strategies, potentially influencing future quotas or compliance levels. Furthermore, the weekly inventory reports – the API Weekly Crude Inventory on April 21st and 28th, and the EIA Weekly Petroleum Status Report on April 22nd and 29th – will provide immediate snapshots of crude and product balances. Should these reports indicate rising inventories, coupled with signals of reduced future shipping demand, it could reinforce a bearish outlook. Finally, the Baker Hughes Rig Count on April 24th and May 1st will offer insights into upstream activity, which could also be influenced by the broader capital discipline trend signaled by these NOC decisions. Investors should monitor these events closely, as they will provide further clarity on how global producers and consumers are reacting to a potentially recalibrated energy demand outlook.


