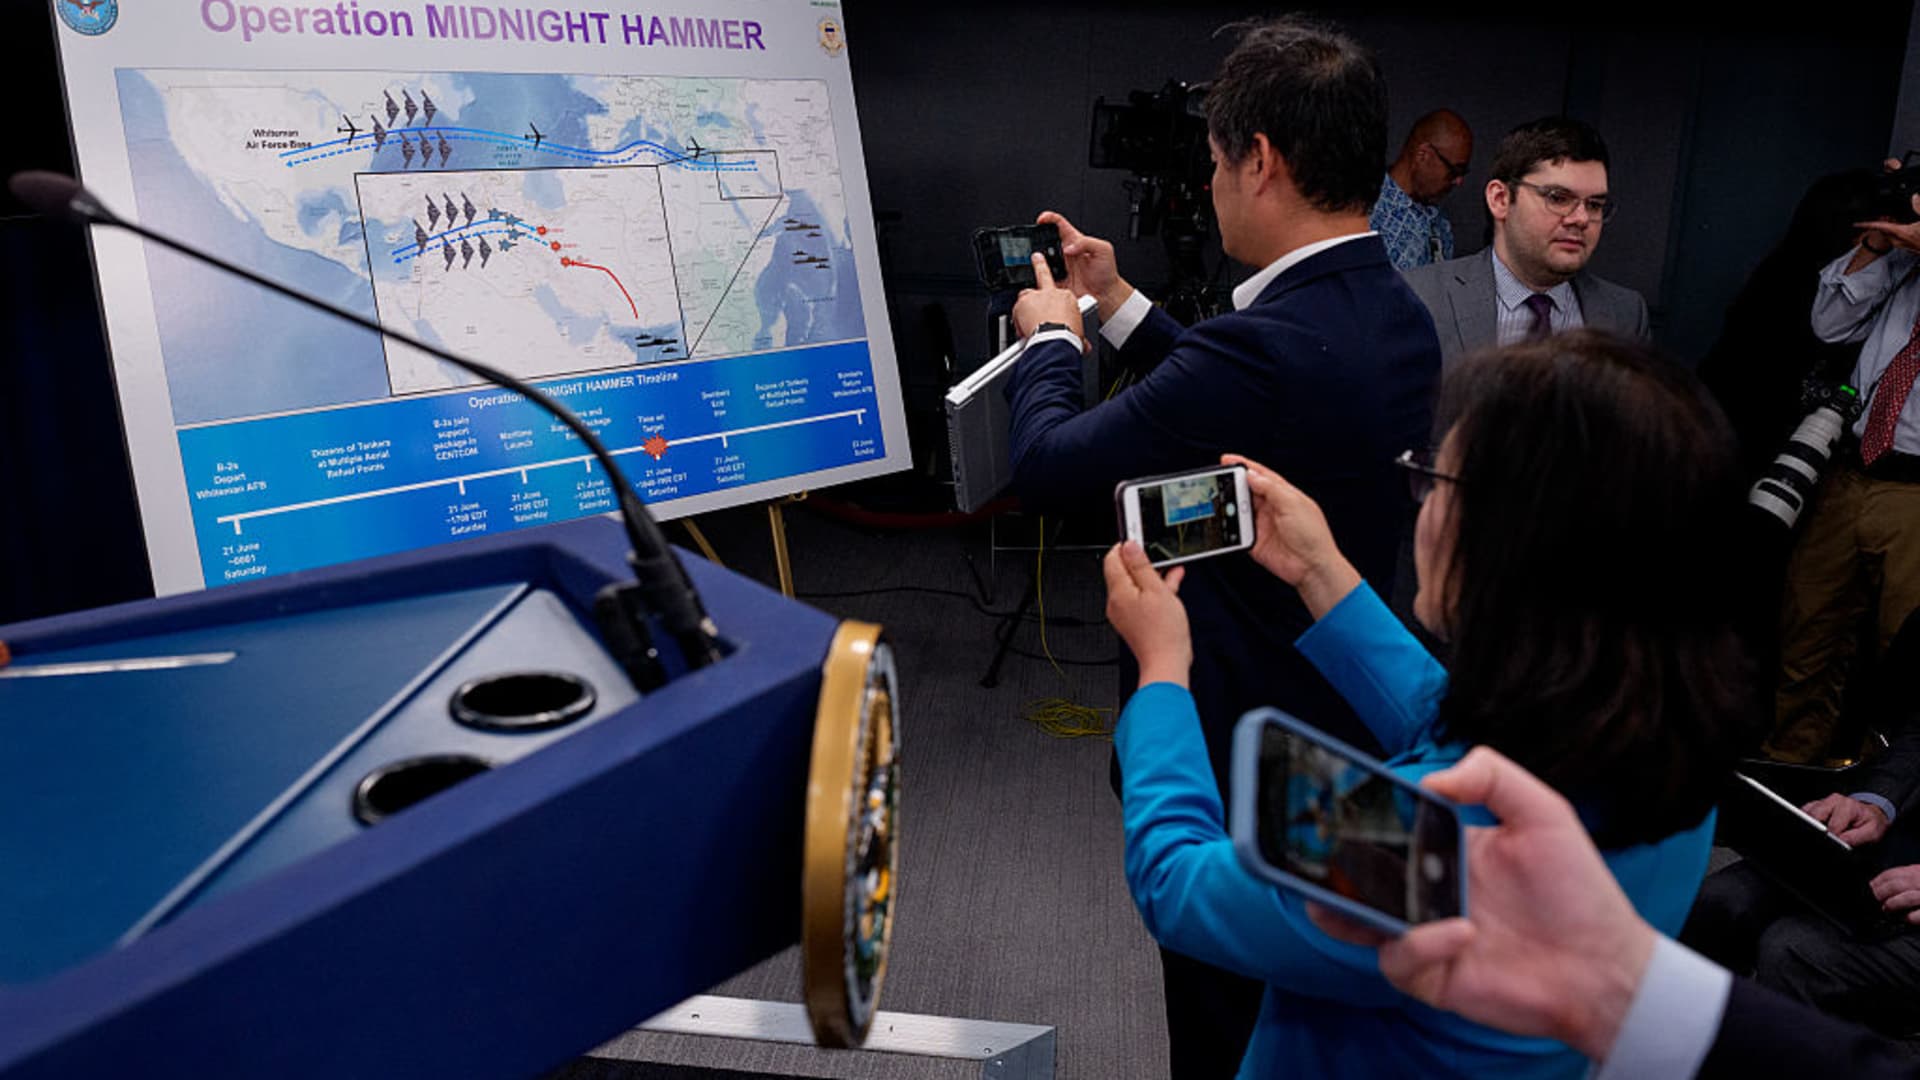
The geopolitical landscape of global energy markets shifted dramatically this past weekend, as the United States launched airstrikes against three of Iran’s nuclear sites. This decisive action, spearheaded by President Donald Trump, defied widespread analyst expectations and a self-imposed “two-week” deliberation timeline, injecting an immediate and substantial new risk premium into crude oil markets. For investors, the immediate challenge is to re-evaluate what was previously considered a stable, albeit volatile, operating environment. This unexpected escalation not only tests the credibility of presidential rhetoric but also fundamentally alters the risk calculus for energy assets, demanding a rapid reassessment of supply security and future price trajectories.
Geopolitical Shockwave and Immediate Market Re-evaluation
The suddenness of the U.S. strikes, coming well ahead of President Trump’s self-declared two-week decision window, has sent a clear message: the ‘Trump Always Chickens Out’ (TACO) trade, a historical pattern of rhetorical threats followed by de-escalation, may no longer apply. This shift in presidential posture has profound implications for how markets will price future geopolitical risks. Historically, the market has often discounted Trump’s more bellicose statements, leading to rebounds when threats were not fully acted upon. This weekend’s events, however, force a recalibration of that expectation, embedding a higher degree of uncertainty into forward guidance.
The immediate market reaction was palpable, with U.S. futures sliding in Sunday evening trading. S&P 500 futures lost 0.17%, Dow Jones Industrial Average futures fell 0.24%, and Nasdaq 100 futures dropped 0.21%, signaling broad market apprehension. While these equity movements might seem modest, they underscore a foundational shift in risk perception. Prior to this weekend, Brent crude had been on a notable downtrend, falling from $102.22 on March 25th to $93.22 by April 14th, a significant 8.8% decline over just two weeks. This previous trend suggested markets were pricing in a more stable, possibly oversupplied, environment. Today, however, that calculus has been overturned. As of today, WTI Crude trades at $91.28, having largely held its ground within a day range of $86.96-$93.3, while Gasoline hovers around $2.96 per gallon, down a modest 0.34% within a range of $2.93-$3.00. These price levels, while not showing an immediate explosion, now underpin a vastly different geopolitical backdrop, one where the risk of supply disruption is significantly higher than it was just days ago.
The Strait of Hormuz: A Critical Chokepoint Under Threat
Perhaps the most immediate and tangible threat to global oil supply stemming from this escalation is Iran’s renewed declaration regarding the Strait of Hormuz. Following the U.S. attacks, Iran’s parliament backed closing the Strait, a sentiment echoed by senior lawmakers. This chokepoint, through which roughly one-fifth of the world’s total petroleum consumption passes daily, is an artery vital to global energy security. Any sustained disruption to shipping in the Strait would send crude prices soaring, regardless of existing inventory levels or demand patterns. The U.S. has already called on China to exert influence to prevent such a closure, highlighting the international community’s acute awareness of this vulnerability. For oil and gas investors, this scenario represents a tail risk that has now moved squarely into the realm of possibility. The previous Brent trend, reflecting a more sanguine view, now appears fundamentally misaligned with this heightened risk, demanding that investors build in a significantly larger geopolitical risk premium into their valuation models. The market’s current stability, represented by WTI near $91, is likely a temporary equilibrium as traders await further clarity on Iran’s retaliatory measures and the potential for a blockade.
Navigating the Unpredictable: Investor Focus and Future Benchmarks
In the wake of these strikes, a key question from our readers revolves around building a base-case Brent price forecast for the next quarter and understanding the consensus 2026 Brent forecast. Frankly, the events of this weekend have largely rendered previous consensus forecasts obsolete. While the consensus 2026 Brent forecast prior to the strikes likely reflected a gradual easing of prices, the current landscape demands a complete re-evaluation. The primary drivers for Brent pricing have dramatically shifted from supply-demand fundamentals and inventory levels to geopolitical risk and potential supply disruptions. Investors must now prioritize scenarios involving regional escalation, Iranian retaliation, and the durability of supply routes, particularly the Strait of Hormuz. The market will be highly sensitive to any rhetoric or action suggesting a blockade or direct confrontation impacting shipping lanes. Furthermore, the question of Chinese teapot refinery operations, another common inquiry, will now be filtered through the lens of supply security. If crude availability becomes constrained, even robust refining demand might struggle to secure feedstocks, impacting product markets like gasoline.
Upcoming Events and Geopolitical Overlay
The coming weeks are packed with critical energy market events, all of which will now be interpreted through the prism of heightened geopolitical tension. The Baker Hughes Rig Count, scheduled for April 17th and 24th, will offer insights into North American supply dynamics, but its impact will likely be overshadowed by Middle East developments. Far more significant will be the OPEC+ meetings: the Joint Ministerial Monitoring Committee (JMMC) on April 18th, followed by the Full Ministerial meeting on April 20th. These gatherings were already pivotal for global supply management, but now they take on an added dimension. Will OPEC+ members, particularly Saudi Arabia, feel compelled to adjust production quotas in light of potential Iranian supply disruptions? Any indication of either increased output to stabilize markets or a reluctance to act could have significant price implications. Additionally, the API Weekly Crude Inventory (April 21st, 28th) and EIA Weekly Petroleum Status Report (April 22nd, 29th) will be scrutinized not just for inventory levels, but for any signs of pre-emptive stocking or shifts in crude flows signaling market anxiety. Investors will be keenly watching for any data points that suggest a tangible impact on global supply chains or a shift in major crude importers’ strategies, all of which will feed into a rapidly evolving oil price outlook.

