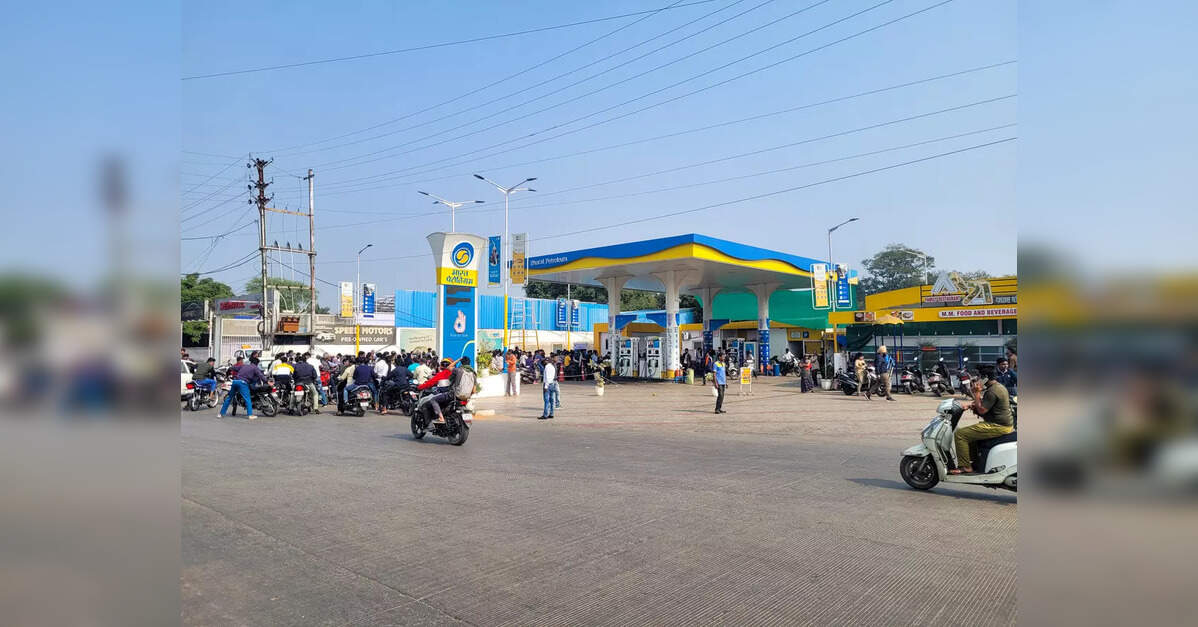
India’s energy landscape is presenting a nuanced picture for investors, with recent data revealing a significant divergence in demand trends across key fuels. While the nation’s appetite for petrol surged to a five-month high in October, fueled by robust festive travel, diesel consumption surprisingly remained flat, defying historical post-monsoon recovery patterns. This internal shift, coupled with broader global crude market volatility, creates a complex environment for energy investors. Analyzing these distinct demand trajectories, alongside the growth in LPG and aviation fuel, is critical for understanding India’s evolving role in the global energy equation and informing strategic investment decisions in the current market climate.
India’s Evolving Demand Mosaic: A Tale of Two Fuels
The latest consumption figures from India underscore a fascinating, and perhaps unexpected, rebalancing within its domestic fuel market. October saw petrol sales climb to 3.65 million tonnes, marking a robust 7% year-on-year increase and a significant jump from September’s 3.4 million tonnes. This surge, primarily attributed to heightened personal mobility and festive season travel, highlights the resilience of India’s consumer-driven economy in certain segments. Year-to-date for the current fiscal year (starting April 2025), petrol consumption has risen by 6.8% to 24.84 million tonnes, indicating sustained momentum.
In stark contrast, diesel, which traditionally accounts for nearly 40% of India’s total fuel consumption, posted a marginal year-on-year drop in October, settling at 7.6 million tonnes, down from 7.64 million tonnes in the same month last year. This flat performance is particularly noteworthy as October typically ushers in a rebound in diesel demand, driven by receding monsoons and increased trucking activity for goods transport during the festive season. The deviation from this historical trend suggests potential underlying shifts in industrial activity, freight logistics, or even a nascent move towards alternative transport solutions. Fiscal year-to-date diesel sales show a more modest 2.45% increase, reaching 53.3 million tonnes, further emphasizing the deceleration compared to petrol.
Growth Pockets: LPG and Aviation Fuel Chart Steady Courses
Beyond the petrol-diesel dichotomy, India’s energy matrix reveals consistent growth in other crucial segments. Liquefied Petroleum Gas (LPG) consumption saw a healthy 5.4% increase in October, reaching almost 3 million tonnes. This growth is largely underpinned by burgeoning household demand, significantly boosted by the government’s subsidized LPG supply scheme, PMUY. The program successfully added 25 lakh new homes, expanding its coverage to 10.58 crore households from 10.33 crore. This initiative continues to be a structural driver for LPG demand, with fiscal year-to-date sales up 7.2% to 19.7 million tonnes, making it a reliable segment for investors seeking stable demand drivers.
Similarly, aviation turbine fuel (ATF) consumption continues its post-pandemic rebound. October figures show a 1.6% month-on-month rise to 769,000 tonnes, representing an impressive 11.11% increase compared to October 2023. This resurgence is indicative of recovering air travel and economic activity, reinforcing the sector’s long-term growth trajectory, which has averaged a 1.65% Compound Annual Growth Rate since 2019. Fiscal year-to-date, ATF consumption stands at 5.2 million tonnes, up 1%. These growth pockets, while smaller in volume than diesel, offer compelling narratives for targeted investments within India’s energy infrastructure.
Global Crude Dynamics and Investor Sentiment: A Volatile Backdrop
While India’s internal demand dynamics offer a mixed but generally growth-oriented picture, the global crude oil market presents a more immediate challenge for investors. As of today, Brent Crude trades at $90.38 per barrel, experiencing a sharp 9.07% decline within the day, with a range between $86.08 and $98.97. Similarly, WTI Crude is at $82.59, down 9.41% today. This significant downward pressure follows a broader trend, with Brent having plummeted by nearly 20% in the last 14 days, from $112.78 on March 30th to its current level on April 17th. Gasoline prices have also felt the pinch, trading at $2.93, down 5.18% today.
This dramatic shift in crude prices has naturally put investors on edge. We’ve observed a surge in reader inquiries reflecting this concern, with many asking about the trajectory of oil prices, specifically, “what do you predict the price of oil per barrel will be by end of 2026?” The current sharp correction suggests that despite pockets of demand strength like India’s petrol and LPG sectors, broader macroeconomic headwinds, inventory builds, or shifts in supply expectations are dominating the narrative. The recent decline introduces significant uncertainty, pushing investors to re-evaluate their long-term price forecasts and short-term market positioning. The divergence between resilient Indian demand segments and a sharply falling global crude price points to a disconnect that requires careful monitoring.
Navigating the Near-Term: Upcoming Catalysts and Strategic Positioning
In this environment of heightened volatility, upcoming events are poised to provide critical directional cues for the crude oil market and, by extension, the cost of refined products globally. Investors are keenly watching the OPEC+ Joint Ministerial Monitoring Committee (JMMC) Meeting on April 19th, immediately followed by the full OPEC+ Ministerial Meeting on April 20th. These gatherings are paramount, especially given the recent significant price decline. A key question on investors’ minds, frequently posed to our AI assistant, concerns “OPEC+ current production quotas” and whether the alliance will adjust its supply strategy in response to market conditions or perceived demand weakness. Any decision on production levels will undoubtedly send ripples across the energy complex.
Closer to home, the weekly inventory reports from the American Petroleum Institute (API) on April 21st and April 28th, alongside the official EIA Weekly Petroleum Status Report on April 22nd and April 29th, will offer crucial insights into the health of U.S. demand and supply balances. These reports often dictate short-term price movements and can influence sentiment. Furthermore, the Baker Hughes Rig Count on April 24th and May 1st will provide a window into future U.S. production intentions. For investors, integrating these upcoming catalysts into their analysis is essential. The interplay between India’s shifting demand profile and these global supply-side and inventory indicators will define the energy market’s trajectory in the coming weeks, demanding a dynamic and responsive investment strategy.


