The Sanctions Squeeze: India’s Crude Supply Under Pressure
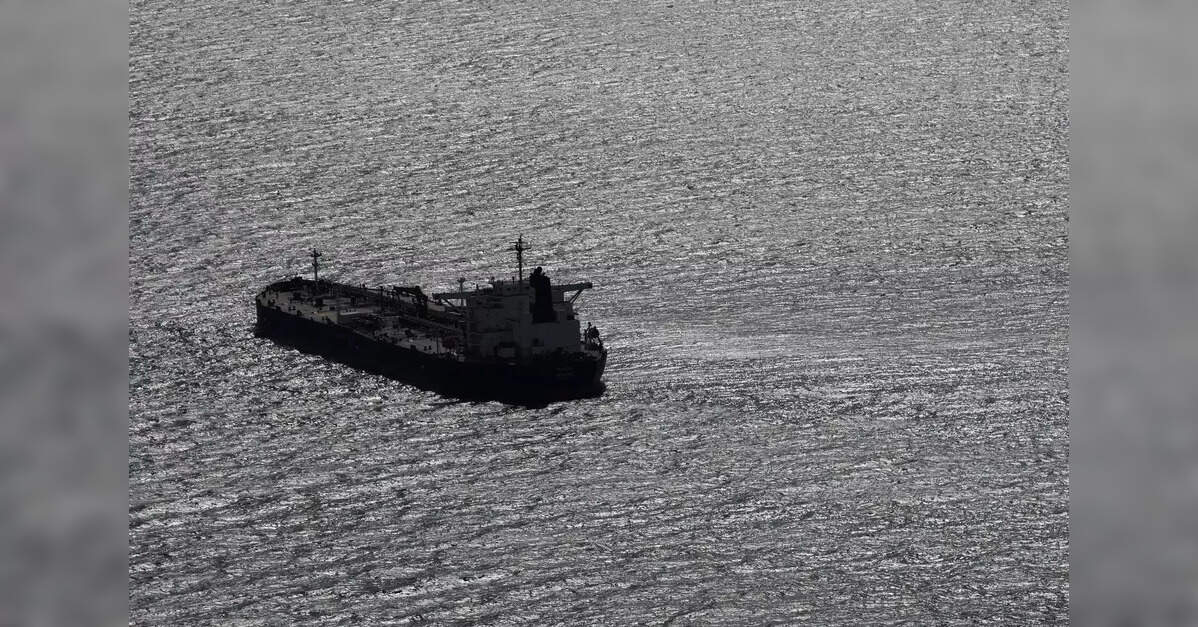
The global oil market is once again navigating turbulent waters, with a recent incident serving as a potent symbol of shifting trade dynamics. An India-bound tanker, the Furia, laden with nearly 730,000 barrels of Urals crude from Russia’s Baltic port of Primorsk, dramatically reversed course in the Fehmarn Belt between Denmark and Germany. This U-turn, occurring just a week after the US tightened sanctions on Russia’s state-owned Rosneft PJSC and fellow energy giant Lukoil PJSC, signals a significant disruption in the crucial oil trade between India and Russia. The US Treasury Department has mandated that transactions involving these entities must be wound down by November 21, forcing a swift recalibration among global refiners and traders.
Indian refiners, long beneficiaries of discounted Russian crude following earlier sanctions, now face a stark reality. Senior executives at major Indian processors have indicated that Russian oil flows are expected to plunge, cutting off a relatively cheap and consistent supply source. The Furia, initially destined for Sikka in India’s Gujarat state by mid-November – a port utilized by private refiner Reliance Industries Ltd. and state-backed Bharat Petroleum Corp. Ltd. (BPCL) – later changed its reported destination to Egypt’s Port Said. While vessels traversing the Suez Canal sometimes use Port Said as an interim waypoint, the Furia’s initial reversal strongly suggests a direct response to the heightened sanctions environment. Reliance, which holds a long-term contract with Rosneft, has already committed to sanctions compliance, actively seeking out Middle Eastern crude alternatives. State refiners, too, have grown increasingly cautious about engaging with US-sanctioned Russian producers, opting for stability over the risk of secondary sanctions.
Market Volatility and Investor Questions Amid Supply Shifts
The tightening of sanctions and the resulting uncertainty in major oil trade routes are contributing to a volatile market environment. As of today, Brent Crude trades at $90.38 per barrel, marking a significant 9.07% decline in a single day, with its trading range stretching from $86.08 to $98.97. Similarly, WTI Crude has seen a sharp drop to $82.59, down 9.41%, within a daily range of $78.97 to $90.34. This sharp daily correction follows a broader downward trend, with Brent shedding nearly 20% from its $112.78 price point just two weeks ago. This rapid depreciation in prices, despite potential supply disruptions, underscores a complex interplay of demand concerns, inventory data, and geopolitical developments.
Our proprietary reader intent data reveals that investors are keenly focused on understanding these market dynamics. A recurring question asks about the predicted price of oil per barrel by the end of 2026, highlighting long-term strategic planning concerns amidst short-term volatility. Another common query revolves around OPEC+’s current production quotas and their potential future adjustments. The Furia incident and the broader implications for Russian supply introduce a new variable into these considerations. While a reduction in Russian crude availability for certain markets might normally be bullish, the current price action suggests that broader demand concerns or alternative supply avenues are taking precedence, or that the market is reacting to a perceived easing of geopolitical tensions elsewhere. Investors are clearly seeking clarity on how these supply shifts will ultimately impact the global supply-demand balance and, consequently, crude benchmarks.
Navigating the Geopolitical Strait: Implications for Global Flows
The Furia’s U-turn is not an isolated event but a symptom of a broader challenge facing Russian crude exports. Beyond direct sanctions, European nations like Denmark are stepping up scrutiny of tankers passing through their waters, specifically targeting older vessels often associated with Russia’s so-called “shadow fleet.” This increased inspection regime adds another layer of complexity and cost to the logistics of moving Russian oil. The vessel’s original destination change to Port Said, while potentially a placeholder, also highlights the critical role of transit choke points like the Suez Canal and the intricate web of global shipping routes now subject to geopolitical pressures.
For investors, this means that even if Russian oil finds alternative buyers, the cost of transport, insurance, and compliance is likely to rise. The reliance on older vessels in the shadow fleet, coupled with heightened inspection risks, could lead to longer transit times, increased demurrage costs, and potential delays or outright refusals of passage. This structural shift in maritime logistics could further fragment global oil markets, creating distinct pricing mechanisms for sanctioned and unsanctioned crude. Companies involved in shipping, refining, and trading must continuously adapt their strategies to navigate these evolving geopolitical constraints and their impact on operational efficiency and profitability.
Ahead of the Curve: Key Events Shaping the Outlook
Looking forward, the global energy calendar is packed with events that will provide crucial signals for investors tracking these evolving supply dynamics. The immediate focus will be on the upcoming OPEC+ Joint Ministerial Monitoring Committee (JMMC) Meeting on April 19th, followed swiftly by the full OPEC+ Ministerial Meeting on April 20th. Given the recent price volatility and the potential for shifts in Russian export patterns due to sanctions, market participants will be closely watching for any indications of production policy adjustments. Will OPEC+ maintain its current quotas, or will the group respond to perceived demand weakness (as suggested by recent price declines) or potential disruptions in Russian supply?
Beyond OPEC+, weekly inventory data will continue to offer vital insights into market balances. The API Weekly Crude Inventory report on April 21st, followed by the EIA Weekly Petroleum Status Report on April 22nd, will shed light on US crude and product stockpiles. These reports are critical for gauging the health of demand in the world’s largest oil consumer and how it might absorb any shifts in global supply. Further, the Baker Hughes Rig Count on April 24th will indicate the ongoing trajectory of North American production. As Indian refiners pivot away from Russian crude, the responsiveness of other suppliers – including those in the Middle East and potentially the US – will be key. Investors should closely monitor these upcoming data releases and policy decisions, as they will undoubtedly shape the trajectory of oil prices and the profitability of energy investments in the coming weeks and months.


