The global oil and gas sector is once again navigating a turbulent landscape, with market sentiment heavily influenced by persistent geopolitical tensions. Recent discussions surrounding a potential U.S.-brokered peace plan for the Russia-Ukraine conflict have sent ripples through energy markets, prompting a re-evaluation of supply dynamics and demand forecasts. While the prospects of a de-escalation initially sparked a bearish reaction, the intricate details and uncertain viability of any proposed resolution continue to inject significant volatility. For oil and gas investors, understanding the interplay between these high-stakes diplomatic efforts, ongoing sanctions, and fundamental market indicators is paramount to positioning portfolios effectively in the coming weeks.
Geopolitical Winds Batter Crude Benchmarks
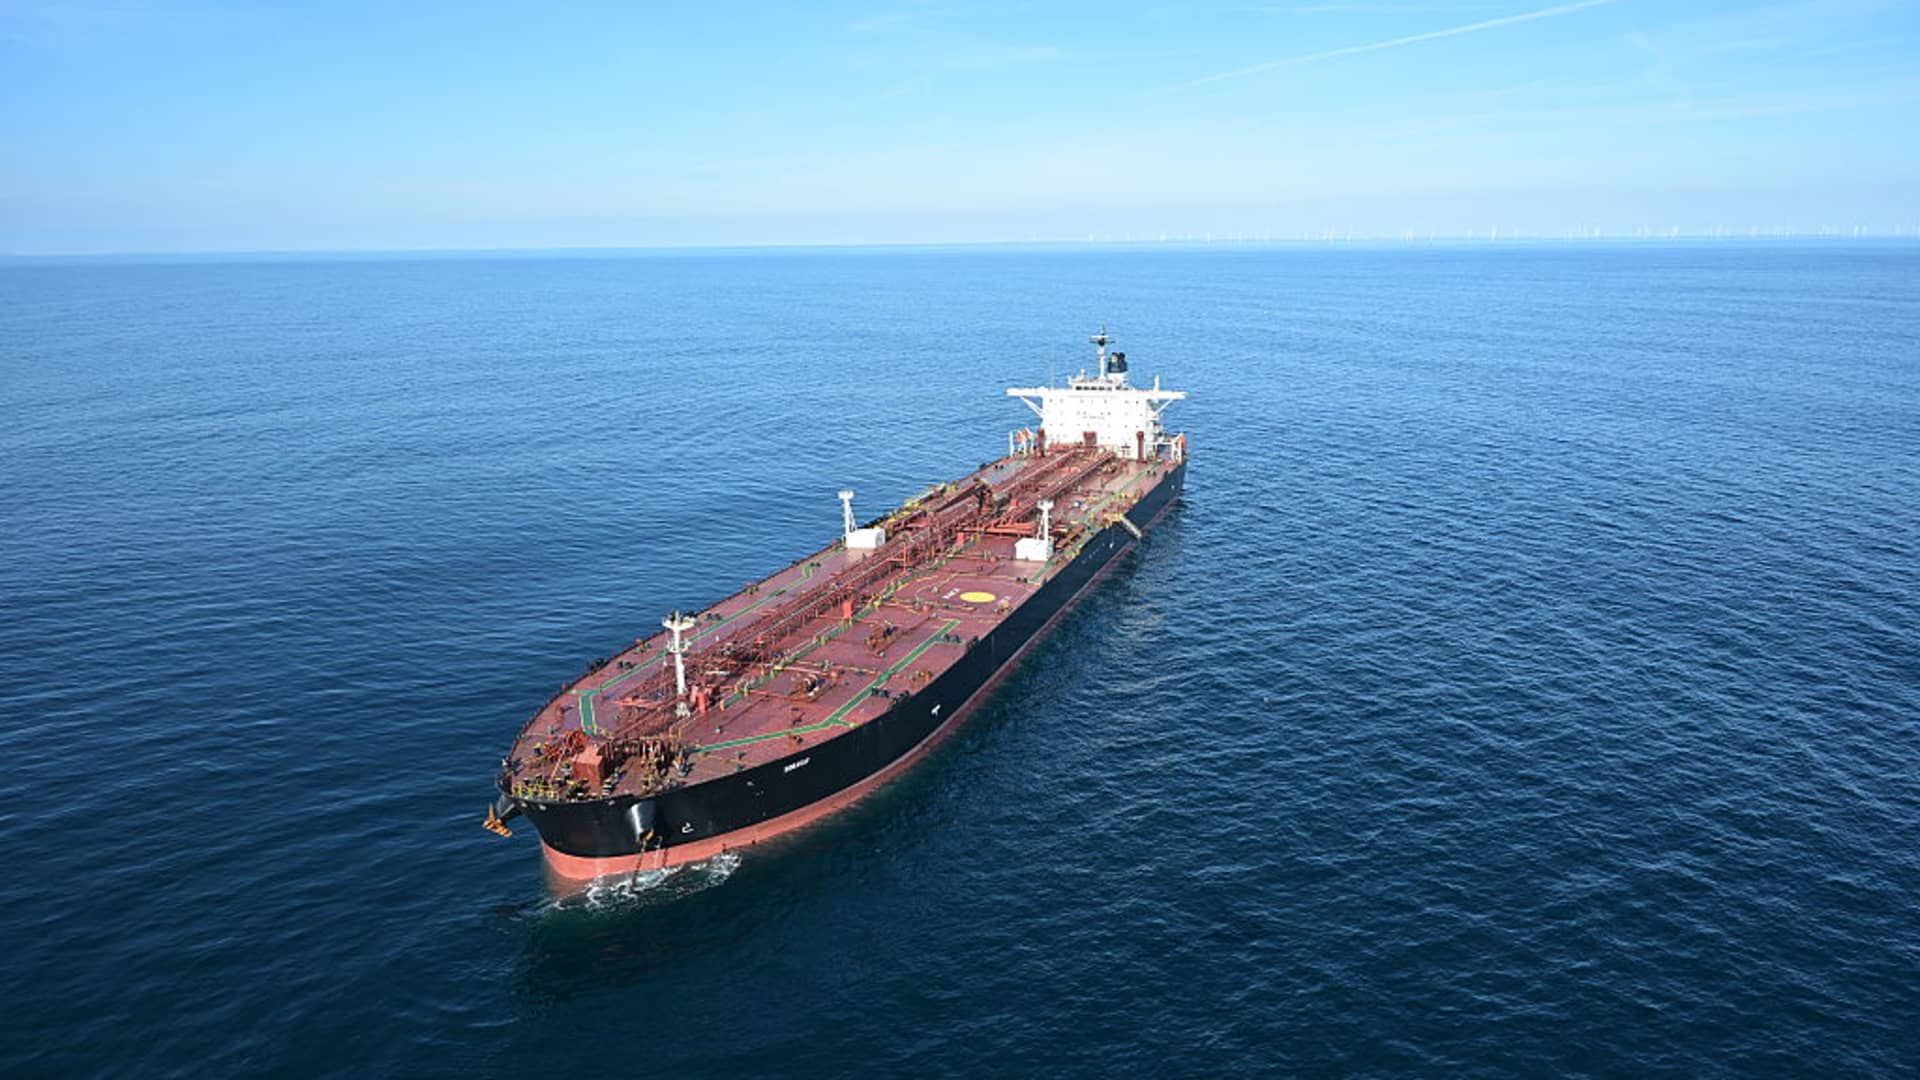
The mere whisper of a peace deal in the protracted Russia-Ukraine conflict has demonstrated its profound ability to sway energy prices, highlighting the market’s sensitivity to geopolitical risk. Reports detailing a U.S.-backed proposal, suggesting territorial concessions and limitations on Ukraine’s military capacity, have fueled speculation about future oil supply stability. While analysts widely express skepticism about the plan’s immediate acceptance by Ukraine, the potential for reduced conflict premium weighed heavily on benchmarks. As of today, April 17th, 2026, international benchmark Brent crude trades at $90.93 per barrel, marking an 8.51% decline within the day, fluctuating between a range of $86.08 and $98.97. Similarly, U.S. West Texas Intermediate (WTI) crude stands at $83.17, down 8.77% for the day, with its trading range between $78.97 and $90.34. This sharp daily correction follows a broader downward trend for Brent, which has fallen over 12% from $112.57 on March 27th to $98.57 just yesterday, April 16th. Such significant movements underscore the market’s reactive nature to any perceived shift in the supply-demand balance, particularly when a major producer like Russia is involved. The ongoing investigation into a suspected Russian “shadow fleet” tanker, the Boracay, further complicates the supply picture, reminding investors that sanctions and their circumvention remain a critical, albeit murky, factor.
Investor Sentiment and the Shadow Fleet’s Persistence
Amidst the geopolitical churn, our proprietary reader intent data reveals a clear focus from investors on understanding the fundamental underpinnings of the energy market. A recurring question this week pertains to OPEC+ production quotas, directly linking to concerns about global supply. The current market volatility, exacerbated by peace plan discussions, places renewed emphasis on the cartel’s strategy. Furthermore, investors are keenly asking about the predicted price of oil per barrel by the end of 2026, signifying a longer-term outlook despite immediate price pressures. These questions highlight a market grappling with contradictory signals: potential peace reducing risk premium versus ongoing supply constraints and persistent demand. The U.S. sanctions against major Russian producers Rosneft and Lukoil, which took effect recently, add another layer of complexity, removing legitimate supply channels and potentially increasing reliance on the “shadow fleet” — tankers operating outside conventional oversight. This clandestine network, as exemplified by the Boracay tanker incident, introduces unquantifiable risks and costs into the global oil trade, making precise supply forecasting an even greater challenge and contributing to the overall uncertainty investors are attempting to price in.
Navigating the Volatility: Key Events on the Horizon
For investors looking to navigate the current market volatility, the immediate future presents several critical calendar events that could significantly re-rate oil prices and energy equities. The upcoming OPEC+ Joint Ministerial Monitoring Committee (JMMC) meeting today, April 17th, followed by the Full Ministerial Meeting tomorrow, April 18th, are paramount. These gatherings will provide crucial insights into the cartel’s production strategy, especially in light of recent price declines and the ongoing geopolitical discussions. Any indication of quota adjustments or a reaffirmation of current cuts will directly impact global supply expectations. Beyond OPEC+, the market will closely monitor the API Weekly Crude Inventory report on April 21st and the EIA Weekly Petroleum Status Report on April 22nd. Consistent inventory builds or drawdowns will offer tangible evidence of demand health and domestic supply trends. Further, the Baker Hughes Rig Count on April 24th will indicate the health of drilling activity and future production capacity in key regions. With another round of API and EIA reports scheduled for April 28th and 29th, respectively, and the subsequent Baker Hughes Rig Count on May 1st, the next two weeks are packed with data points that could either stabilize or further disrupt the market’s current delicate balance. Proactive investors will be dissecting every release for signals on supply, demand, and producer sentiment.
Outlook for Energy Equities Amidst Uncertainty
The current market environment, characterized by sharp crude price corrections and geopolitical uncertainty, naturally casts a shadow over energy equities. Major oil and gas companies have felt the pressure, with Europe’s Stoxx Oil and Gas index registering significant declines in recent trading sessions. Giants like Shell and BP have seen their stock values decrease, while Germany’s Siemens Energy experienced an even more pronounced downturn. Even U.S. stalwarts such as Exxon Mobil and Chevron have not been immune to the premarket pressures. This broad-based decline across the sector indicates that investors are pricing in a lower-for-longer oil price scenario, or at least a period of heightened volatility. While a genuine peace deal could, in theory, reduce the geopolitical risk premium, its potential to normalize Russian supply faster than anticipated poses a downside risk to crude prices, thereby impacting upstream profitability. Conversely, if the peace plan falters, the ongoing conflict and sanctions could maintain a floor under prices, albeit with increased operational risks and potential for supply disruptions. Investors should closely monitor the quarterly earnings reports from these companies in the coming weeks, analyzing their guidance on capital expenditures, production targets, and dividend policies, as these will be key indicators of how management teams are planning to navigate this complex and unpredictable market landscape.

