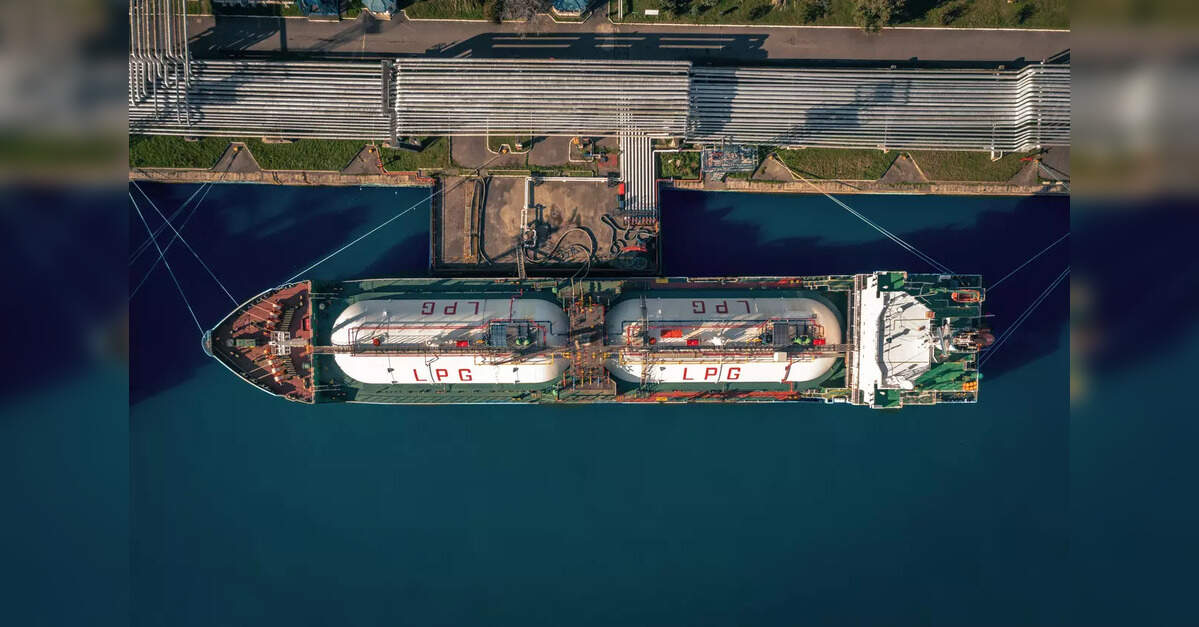
India’s strategic pivot in its liquefied petroleum gas (LPG) procurement marks a significant shift in global energy trade dynamics, offering both opportunities and challenges for investors monitoring the oil and gas sector. State-owned refiners in India are making a concerted move to ramp up imports of US-sourced LPG, targeting approximately 2 million metric tons by 2026 through competitive tenders. This decision signals a deliberate reduction in reliance on traditional Middle Eastern suppliers and is inextricably linked to New Delhi’s broader diplomatic and economic ambitions with Washington, including a commitment to elevate US energy purchases from $10 billion to $25 billion. For sophisticated investors, this isn’t merely a supply chain adjustment; it’s a profound geopolitical rebalancing act with tangible implications for regional energy security, trade relationships, and the long-term positioning of key players in the global LPG market.
The Geopolitical Imperative Behind India’s LPG Shift
India’s planned increase in US LPG imports is a multi-faceted strategic maneuver. On one front, it strengthens the burgeoning economic ties between India and the United States, aiming for a bilateral trade target of $500 billion by 2030. This energy diversification plays a crucial role in securing a comprehensive trade deal, which could see India scrap import taxes on certain US products, including LPG. From a geopolitical perspective, the move addresses US concerns regarding India’s continued purchases of Russian oil, a revenue source Washington asserts is funding Moscow’s conflict in Ukraine. The commitment to increase US energy imports and statements from Indian leadership about potentially ceasing Russian oil purchases underscore a calculated alignment with Western allies. For investors, this shift highlights how geopolitical considerations increasingly drive energy procurement decisions, potentially de-risking supply chains for India while opening new, high-volume export avenues for US producers. India, having imported roughly 65% of its 31 million tons of LPG consumption in 2024, with 90% of its 20.4 million tons imported by refiners under term deals from the Middle East, is now actively diversifying a critical component of its domestic energy mix, which is primarily used as cooking fuel.
Market Volatility and the Investor’s Lens
The energy market currently presents a complex picture of volatility, against which India’s long-term strategic shifts must be viewed. As of today, Brent crude trades at $90.38 per barrel, reflecting a significant 9.07% decline within the day, while WTI crude is at $82.59, down 9.41%. Similarly, gasoline prices have dipped to $2.93, a 5.18% drop. This recent downturn follows a broader trend, with Brent crude having fallen by nearly 20% from $112.78 just two weeks ago. Such sharp movements underscore the market’s sensitivity to global supply-demand signals, inventory data, and geopolitical developments. Many investors are currently asking about the trajectory of crude prices towards the end of 2026, and India’s shift, while focused on LPG, is a signal of demand diversification that could subtly influence overall energy sentiment. While LPG pricing mechanisms are distinct from crude, the underlying principle of supply security and trade relationships remains paramount. US LPG exporters stand to benefit from this new, significant demand channel, potentially stabilizing their long-term off-take volumes and warranting investor attention to infrastructure and logistics providers enabling these transatlantic flows.
Implications for Traditional Middle Eastern Suppliers
India’s decision to cut LPG imports from the Middle East will undeniably have ramifications for its long-standing suppliers. In 2024, India was a major client for Middle Eastern producers, importing 8.1 million tons from the UAE, 5 million tons from Qatar, 3.4 million tons from Kuwait, and 3.3 million tons from Saudi Arabia, alongside smaller volumes from Bahrain and Oman. These state refiners have already signaled their intent to reduce purchases from these traditional partners. While the exact scale of the reduction isn’t yet fully clear, projections suggest India aims to source approximately 10% of its cooking gas imports from the US starting in 2026. This means Middle Eastern producers will need to either find alternative markets for these volumes or adjust their production and export strategies. For investors holding positions in companies like Saudi Aramco (which declined comment on the matter) or national oil companies in the UAE, Qatar, and Kuwait, this development warrants close monitoring. It highlights the increasing competition in global energy markets and the need for producers to adapt to evolving demand patterns and geopolitical pressures, potentially impacting future contract negotiations and market share for LPG exports.
Navigating Future Market Signals and Investment Opportunities
The coming weeks are packed with events that will shape the immediate future of energy markets, providing crucial context for long-term strategic shifts like India’s LPG procurement. The upcoming OPEC+ Joint Ministerial Monitoring Committee (JMMC) Meeting on April 19th, followed by the full OPEC+ Ministerial Meeting on April 20th, will be particularly critical. Investors are keenly interested in OPEC+’s current production quotas and any potential adjustments that could impact global supply. These meetings, combined with weekly data releases such as the API and EIA Weekly Petroleum Status Reports (due April 21st, 22nd, 28th, and 29th) and the Baker Hughes Rig Count (April 24th, May 1st), will offer insights into current supply-demand balances and production trends. For investors, understanding how these near-term market signals interact with long-term demand shifts—such as India’s increasing appetite for US LPG—is paramount. Companies with robust US LPG export capabilities, those investing in shipping and logistics for transatlantic routes, and even those in the financial sector facilitating these massive trade flows, may present compelling investment opportunities as India solidifies its position as a significant and diversified energy consumer on the global stage.


