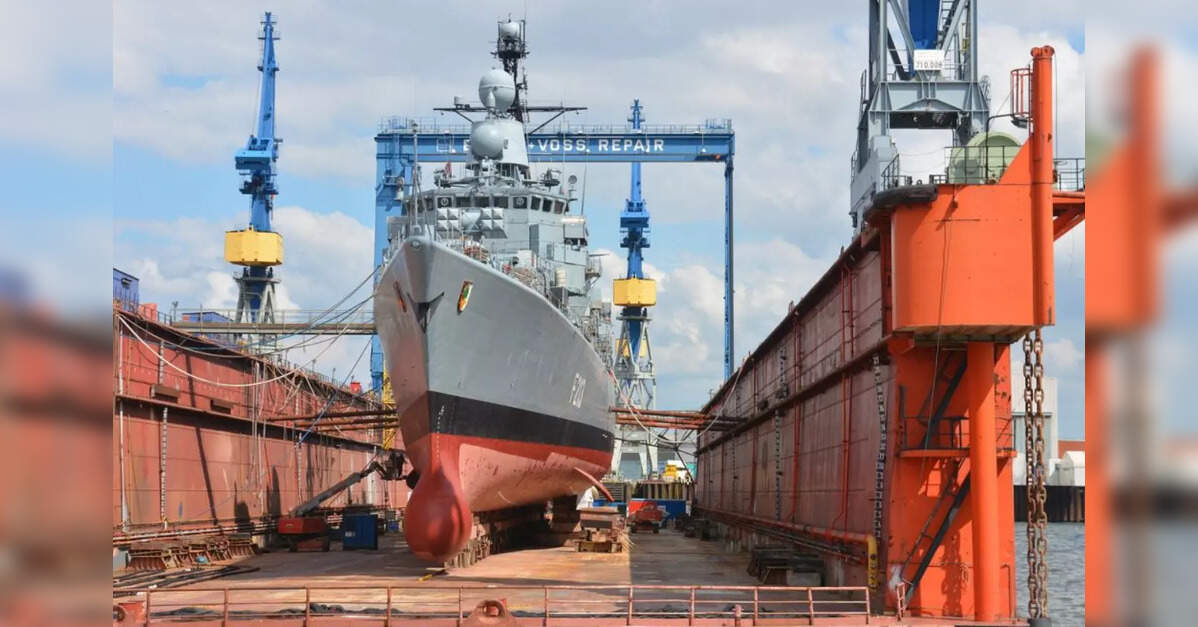
The global energy landscape is undergoing a profound transformation, driven by both decarbonization mandates and a strategic imperative for supply chain diversification. A recent landmark agreement, signaling India’s emergence as a key player in specialized shipbuilding, underscores these shifts and offers significant implications for oil and gas investors. The commitment by a major international container carrier to construct six small, liquefied natural gas (LNG)-powered box ships in India represents an inflection point, not just for maritime logistics, but for the broader energy transition, highlighting growing demand for natural gas as a marine fuel and new investment opportunities in supporting infrastructure.
India’s Strategic Pivot in Global LNG Shipping
India is rapidly positioning itself as a formidable alternative to established shipbuilding giants like China and South Korea, a strategic move bolstered by significant government backing. The recent letter of intent with Cochin Shipyard for six LNG-powered container ships, valued at approximately $300 million, marks the first time a global mainline ship operator has placed such an order in India. These vessels, each with a capacity of 1,700 twenty-foot equivalent units (TEU), will be entirely powered by LNG, aligning with the global shipping industry’s urgent push towards decarbonization. This deal is a direct outcome of India’s ambitious shipbuilding agenda, which includes a substantial Rs 69,725-crore package approved by the Cabinet to enhance domestic capabilities and aims to elevate the nation from its current 16th global ranking to the top 10 by 2030, and ultimately into the top five by 2047. The decision by a leading global carrier to flag these new ships in India further cements the nation’s growing influence in the maritime sector, signaling a long-term commitment that will inevitably fuel demand for LNG bunkering infrastructure and related natural gas supply chains.
Market Volatility and the LNG Investment Calculus
The investment thesis for LNG as a marine fuel, while fundamentally driven by long-term environmental goals, must navigate the immediate realities of a volatile energy market. As of today, Brent Crude trades at $90.38, reflecting a significant decline of 9.07% within the day’s range of $86.08 to $98.97. Similarly, WTI Crude has seen a sharp drop of 9.41%, settling at $82.59, moving within a daily band of $78.97 to $90.34. This downturn is part of a broader trend, with Brent plummeting by nearly 20% from $112.78 just two weeks prior. Such pronounced declines in crude prices inevitably impact the relative cost-effectiveness of traditional bunker fuels versus LNG. While the environmental imperative for LNG adoption remains, a prolonged period of lower crude prices could, in the short-to-medium term, alter the economic payback period for investments in LNG-fueled vessels and infrastructure. Investors must keenly monitor the spread between crude oil and natural gas prices, recognizing that while the long-term trajectory for cleaner fuels is clear, market dynamics can introduce significant tactical considerations for capital deployment in the energy transition space.
Investor Focus: Navigating Geopolitics and Future Energy Demand
Oil and gas investors are currently grappling with significant uncertainties, a sentiment reflected in the most frequent questions posed by our readers. Many are intensely focused on predicting the future, asking “What do you predict the price of oil per barrel will be by end of 2026?” This highlights a pervasive need for clarity on long-term price stability amidst current volatility. The strategic shift towards LNG in shipping, exemplified by India’s burgeoning shipbuilding industry, directly addresses this future outlook by creating new demand centers for natural gas. This diversification away from purely oil-based marine fuels offers a degree of insulation from crude price swings for companies positioned in the natural gas value chain. Furthermore, the emphasis on India as an alternative manufacturing hub speaks to a broader geopolitical trend of supply chain resilience and diversification, reducing reliance on single regions. For investors, this translates into opportunities across the natural gas spectrum, from upstream production and liquefaction to midstream transportation and downstream bunkering facilities, all supporting the expansion of LNG’s role in global commerce and the energy transition.
Upcoming Events Shaping the Near-Term Energy Outlook
The immediate future holds several critical events that will undoubtedly shape the crude oil market and, by extension, influence the broader energy investment landscape. Investors should closely monitor the OPEC+ Joint Ministerial Monitoring Committee (JMMC) Meeting scheduled for April 19th, followed by the full OPEC+ Ministerial Meeting on April 20th. These gatherings are pivotal for determining crude production quotas, and their outcomes could either exacerbate the recent price declines or signal a potential market stabilization or rebound. Beyond OPEC+, weekly data releases provide crucial insights into supply-demand fundamentals. The API Weekly Crude Inventory reports on April 21st and 28th, alongside the EIA Weekly Petroleum Status Reports on April 22nd and 29th, will offer a granular view of U.S. crude stocks and refinery activity. Furthermore, the Baker Hughes Rig Count on April 24th and May 1st will indicate trends in North American drilling activity. The confluence of these events will provide essential context for assessing the short-term trajectory of crude prices, which in turn informs the competitive positioning and investment attractiveness of alternative marine fuels like LNG. Understanding these catalysts is vital for any investor navigating the complex interplay between traditional energy markets and the accelerating global energy transition.


