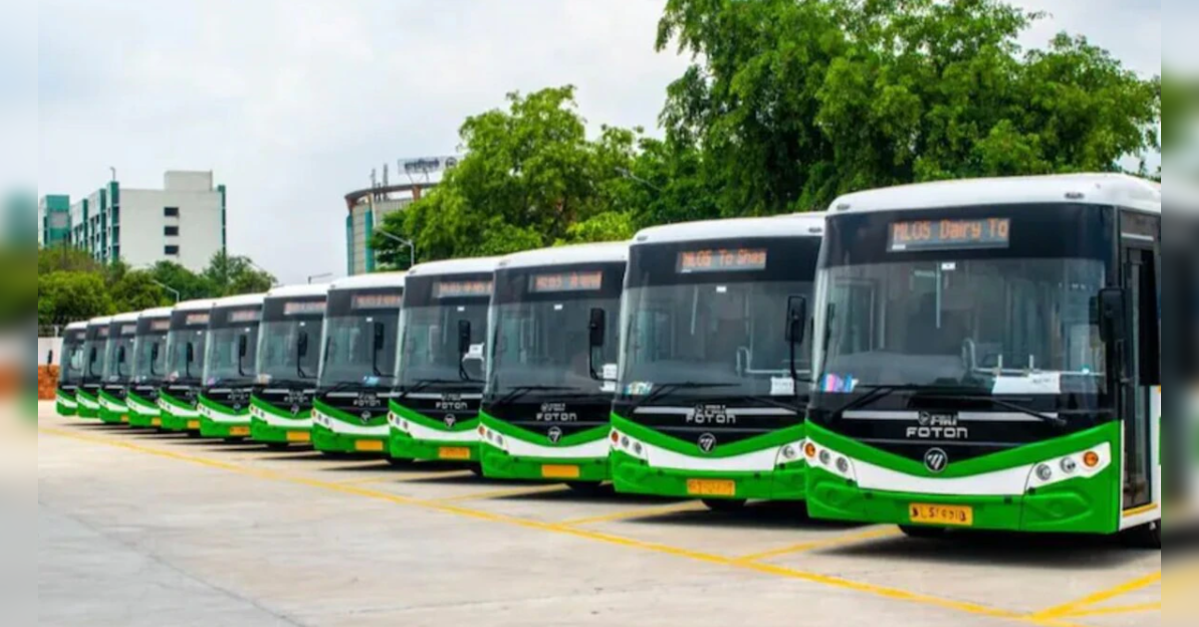
Delhi’s ambitious plan to completely phase out its Compressed Natural Gas (CNG) public bus fleet by August 2031, replacing it entirely with electric vehicles, signals a clear and irreversible shift in urban energy consumption. While the immediate impact on global natural gas demand may seem localized, this policy decision by one of the world’s largest megacities provides a crucial lens through which to view the accelerating energy transition and its long-term implications for oil and gas investors. This move, driven by environmental goals and supported by years of strategic government funding decisions, underscores the growing imperative for investors to evaluate energy portfolios with an eye on both micro-level policy changes and macro-level market dynamics.
Delhi’s Phased Exit: A Concrete Shift in Gas Demand
The National Capital Territory of Delhi has laid out a definitive roadmap to retire its current fleet of 2,743 CNG buses over the next eight years, with a full transition to electric vehicles targeted by August 2031. This includes 993 buses operated by the Delhi Transport Corporation (DTC) and 1,750 under private Cluster operators. Notably, DTC’s older CNG buses, many procured before the 2010 Commonwealth Games, are slated for retirement by 2026-27, with all private Cluster CNG buses following suit by 2031. This policy is not merely a proposal; it’s a committed strategy, reinforced by the fact that neither central nor Delhi governments have allocated funds for new CNG bus purchases in over five years, directing investment exclusively towards electric mobility solutions.
To put this into perspective, if an average city bus consumes approximately 60 kilograms of CNG per day, the full transition of 2,743 buses represents a potential demand reduction of over 164,500 kilograms of CNG daily, or roughly 60,000 tonnes annually, from Delhi’s public transport sector alone. While a single city’s bus fleet might not dramatically alter global gas markets, Delhi’s scale and its pioneering role in public transport electrification serve as a powerful precedent for other major urban centers in India and across emerging economies. Investors should view this as a tangible, long-term erosion of demand for natural gas in a key end-use sector, signaling the growing vulnerability of gas infrastructure investments tied to urban mobility.
Market Volatility and the Energy Transition’s Undercurrents
The evolving energy landscape, marked by both short-term market volatility and long-term structural shifts, demands a nuanced investor approach. As of today, Brent Crude trades at $90.38, reflecting a significant daily downturn of 9.07% and a wider 14-day decline from $112.78 on March 30th to $91.87 yesterday. WTI Crude mirrors this trend, currently at $82.59, down 9.41% for the day. This immediate market turbulence, often driven by geopolitical events or supply-demand sentiment, can overshadow the profound, gradual changes underway in energy consumption patterns.
Delhi’s CNG phase-out is a stark reminder that while crude oil prices may fluctuate, the underlying forces driving the energy transition – policy mandates, technological advancements, and environmental concerns – are steadily reshaping demand for fossil fuels. The decline in gasoline prices, currently at $2.93, down 5.18% today, further illustrates the broader pressure on traditional transportation fuels. For oil and gas investors, these local policy shifts, even in the context of broader commodity price swings, highlight the importance of assessing exposure to specific fuel types and regions, particularly those facing aggressive electrification mandates. The long-term trajectory indicated by Delhi’s decision suggests that the ‘peak demand’ conversation extends beyond crude oil to natural gas in specific, high-visibility sectors like public transport.
What Investors Are Asking: Navigating the Future of Energy Investments
Our proprietary reader intent data reveals a consistent theme among investors: a deep concern for future oil price trajectories and the stability of global supply. Questions like “What do you predict the price of oil per barrel will be by end of 2026?” and “What are OPEC+ current production quotas?” underscore the persistent uncertainty in the market. While OPEC+ decisions and crude inventory reports are critical for short-to-medium term price discovery, policies like Delhi’s bus electrification plan provide crucial insights into the long-term demand side of the equation.
This localized policy directly impacts the investment thesis for companies involved in natural gas distribution, infrastructure, and even those with diversified energy portfolios. It prompts investors to consider how widespread such policies might become and their cumulative effect on global natural gas demand. For those asking about the future of oil prices, Delhi’s move is a powerful signal of the broader energy transition at play, suggesting that structural demand erosion for fossil fuels, whether oil or gas, will be an increasingly important factor in long-term price predictions. Companies failing to adapt their strategies to capitalize on the shift towards electric mobility and renewable energy sources risk being left behind, regardless of short-term commodity price movements.
Upcoming Catalysts: Monitoring Signals for Gas and EV Infrastructure
The coming weeks are packed with events that will provide further insights into the global energy market, offering both immediate trading opportunities and long-term strategic signals. The OPEC+ Joint Ministerial Monitoring Committee (JMMC) meeting on April 18th, followed by the Full Ministerial Meeting on April 19th, will be closely watched for any adjustments to production quotas, directly influencing crude supply and market sentiment. Subsequent API and EIA Weekly Crude Inventory and Petroleum Status Reports on April 21st, 22nd, 28th, and 29th, alongside the Baker Hughes Rig Count on April 24th and May 1st, will offer granular data on U.S. supply and demand dynamics.
For investors, while these events largely focus on crude oil, they exist within a broader context where demand for fossil fuels is under increasing scrutiny. The Delhi CNG bus phase-out, while not directly tied to these immediate events, serves as a powerful reminder of the underlying structural changes occurring. Companies strategically positioned in the EV charging infrastructure, battery technology, or renewable energy sectors stand to benefit from such long-term policy shifts. Therefore, investors should not only monitor the immediate market reactions to OPEC+ decisions and inventory reports but also keep a vigilant eye on policy developments in key emerging markets like India, as these will increasingly shape the long-term investment landscape for natural gas and the broader energy sector.


