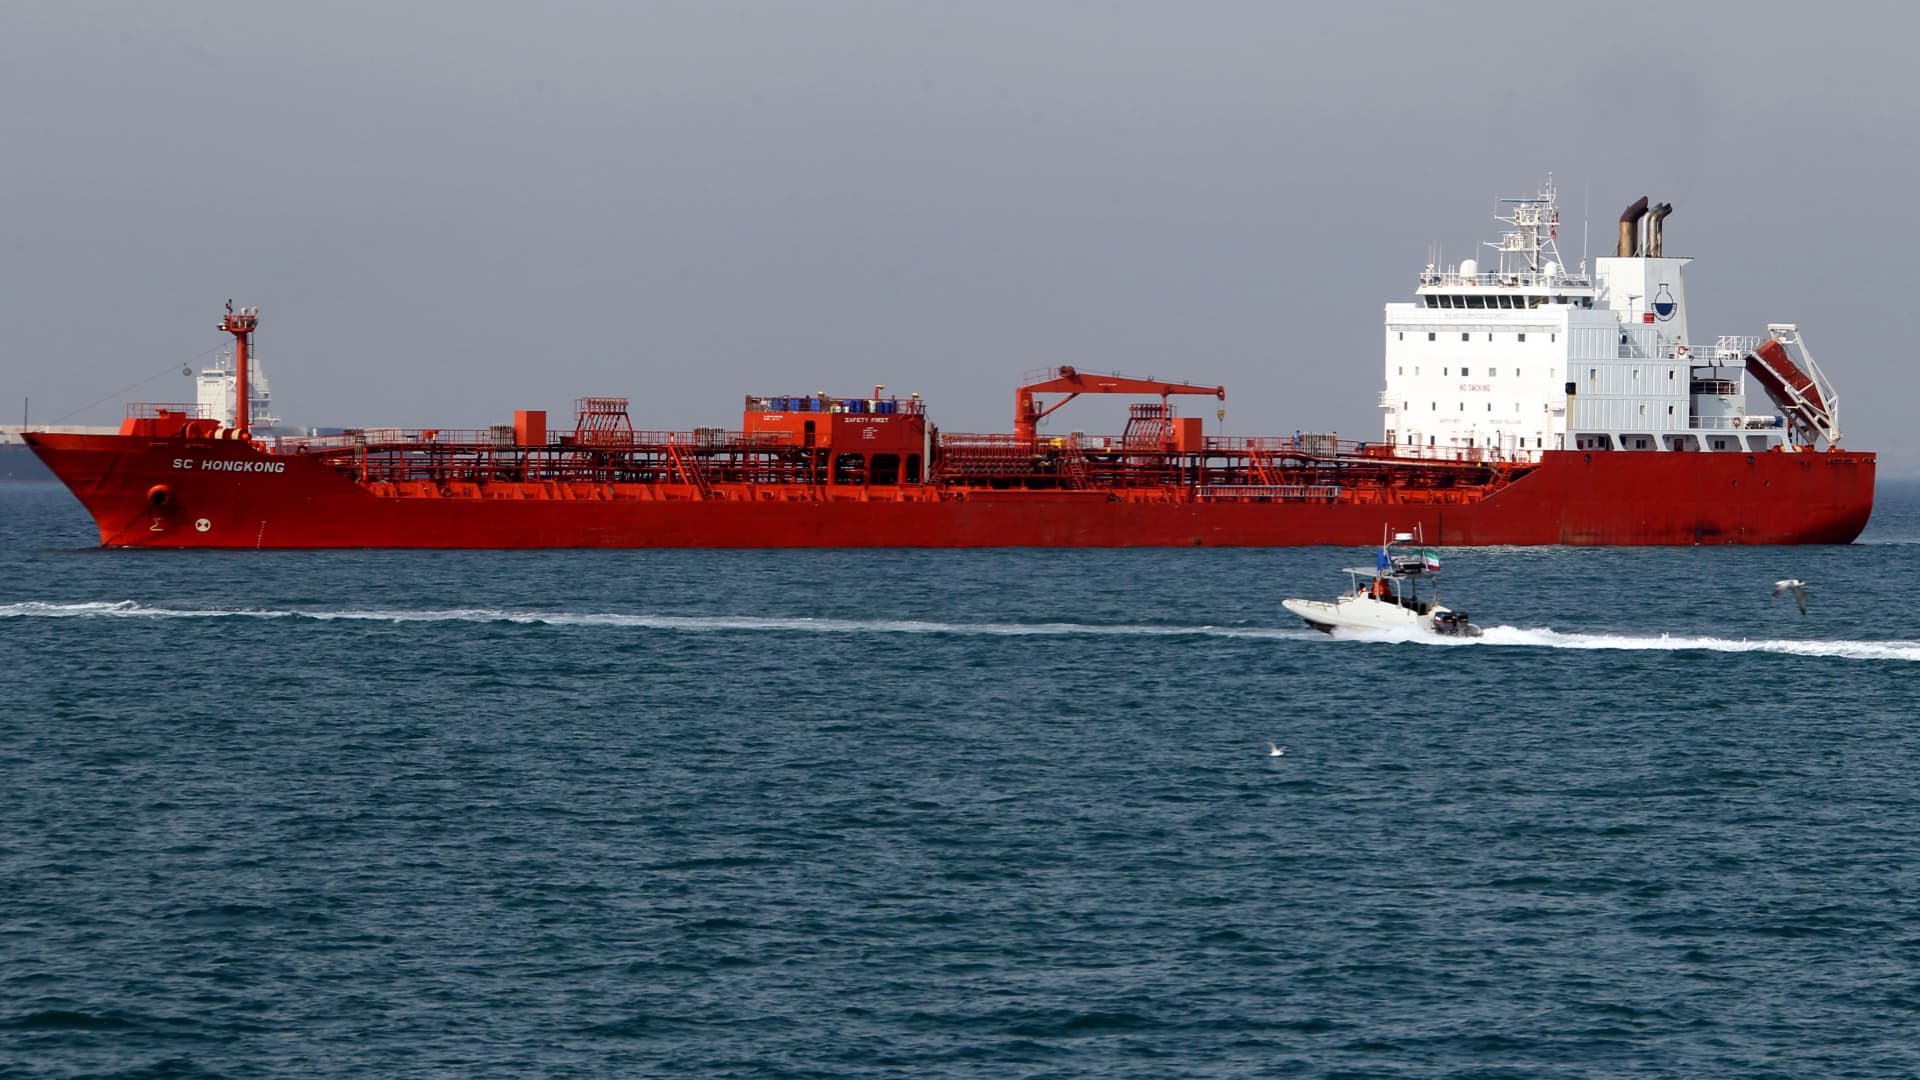
The global oil markets have experienced a significant repricing event driven by a pivotal shift in U.S. policy towards Iran, following a recently brokered ceasefire with Israel. This development has profoundly impacted the geopolitical risk premium embedded in crude prices, leading to initial sharp declines as fears of a major Middle East supply disruption receded. However, as the market processes these changes, a more nuanced picture emerges, demanding careful consideration from investors navigating this evolving landscape.
Repricing Geopolitical Risk: The Iran Concession
The immediate catalyst for the market’s reaction was President Trump’s announcement confirming that China can continue to purchase oil from Iran. This statement signals a notable easing of the “maximum pressure” campaign previously enforced by the U.S. on the Islamic Republic, coming on the heels of a fragile ceasefire with Israel. For the oil market, this development immediately translated into a significant reduction in the perceived risk of supply disruptions from the Middle East, a region vital to global energy flows.
Initial market sentiment saw global benchmark Brent crude fall sharply by $3.33, or 4.66%, while U.S. crude oil dropped by $3.18, or 4.64%. These declines brought prices down to levels not seen since before the recent escalation of conflict between Israel and Iran on June 13. Investors had been keenly watching for potential flashpoints, including fears that Israel might target Iran’s 3.3 million barrels per day (bpd) production capacity or that Tehran might retaliate by disrupting critical energy infrastructure in Gulf nations or, most critically, attempting to close the Strait of Hormuz. The Strait, a chokepoint for 20% of the world’s crude oil, posed a significant threat to shipments from major exporters like Saudi Arabia, the UAE, Iraq, Kuwait, and Bahrain. The U.S. concession, coupled with the ceasefire, dramatically diminished these immediate supply-side fears, leading to a swift adjustment in the risk premium.
Iran’s Potential Supply Re-entry and China’s Demand Dynamics
The implications of China being permitted to continue purchasing Iranian oil are substantial for global supply balances. Iran typically exports approximately 1.7 million bpd, with the vast majority historically destined for China. The crucial question for investors now revolves around the speed and scale at which this volume, previously constrained by sanctions, can fully re-enter the global market. Any significant increase in Iranian crude availability would add supply into a market that has been, at times, precariously balanced.
From a demand perspective, this development directly addresses a key area of investor interest: the operational dynamics of Chinese “tea-pot” refineries. These independent refiners often seek out discounted crude, and increased availability of Iranian oil could provide a significant boost to their feedstock options, potentially leading to higher refinery runs and impacting regional refined product markets. While the immediate impact is a dampening effect on crude prices due to increased supply, the longer-term implications for product spreads and refining margins in Asia warrant close monitoring. The re-entry of Iranian barrels could also put pressure on other producers vying for market share in the crucial Asian demand centers.
Current Market Recalibration: Navigating Volatility
While the initial news of the U.S. concession saw crude benchmarks tumble, the market has since exhibited a degree of recalibration. As of today, Brent crude trades at $95.35 per barrel, marking a modest +0.59% gain for the day, with an intra-day range between $91 and $96.89. Similarly, WTI crude stands at $92.46 a barrel, up +1.29%, having traded between $86.96 and $93.3. This current resilience follows a notable -$9, or -8.8%, decline in Brent over the past two weeks, moving from $102.22 on March 25th to $93.22 on April 14th, illustrating the broader downward pressure that was amplified by the Iran news. Gasoline prices are also reflecting some upward momentum today, trading at $3.02, a +1.68% increase.
This market behavior suggests that while the geopolitical risk premium has been significantly curtailed, other fundamental factors or a lingering, albeit reduced, risk component may still be supporting prices. The sharp initial drop indicates the market’s sensitivity to perceived supply increases, but the subsequent partial recovery suggests that the full implications of Iranian oil re-entry are still being assessed, or that underlying demand strength and existing supply constraints are providing a floor. Investors are keenly analyzing whether the recent price floor represents a new equilibrium, or if further downside is possible as more clarity emerges on the actual volumes and timing of Iranian crude hitting the market.
Upcoming Catalysts and Forward Price Discovery
With the geopolitical landscape shifting, investors are now keenly looking for the next set of signals to inform their strategies, particularly concerning the base-case Brent price forecast for the next quarter – a question frequently posed by our readers. The near-term calendar is packed with events that will shape market sentiment and price discovery. Crucially, the OPEC+ Joint Ministerial Monitoring Committee (JMMC) meeting on April 18th, followed by the Full Ministerial Meeting on April 20th, will be under intense scrutiny. Will the cartel adjust its production quotas in anticipation of potential increased Iranian supply? Any decision here will have profound implications for global crude balances.
Beyond OPEC+, weekly inventory data provides critical insights into real-time supply and demand. The API Weekly Crude Inventory report on April 21st and the EIA Weekly Petroleum Status Report on April 22nd, with subsequent reports on April 28th and April 29th, will be essential for gauging U.S. crude stocks, refinery utilization, and product demand. These reports, alongside the Baker Hughes Rig Count on April 17th and April 24th, which tracks U.S. drilling activity, will help build a comprehensive picture of the market’s immediate trajectory. The interplay between these fundamental data points and the evolving Iranian supply situation will be key to determining the consensus 2026 Brent forecast, which is likely to see downward revisions if a significant and sustained increase in Iranian exports materializes.
Investment Implications and Remaining Headwinds
For energy investors, the U.S. concession on Iranian oil marks a significant recalibration of the market’s risk profile. While the immediate threat of a major Middle East supply disruption has diminished, the potential for increased Iranian supply introduces a new element of bearish pressure on crude prices. This scenario could benefit refiners through lower feedstock costs, while potentially squeezing margins for exploration and production (E&P) companies. Midstream operators, however, may see increased volumes flowing through their infrastructure if Iranian exports ramp up.
Despite the de-escalation, investors should remain cognizant of lingering geopolitical risks. President Trump’s accusations that both Iran and Israel were violating the ceasefire early on Tuesday serve as a reminder of the inherent volatility in the region. The path to full normalization of Iranian oil flows is rarely smooth, and political rhetoric or unforeseen events could quickly reintroduce uncertainty. Therefore, while the immediate market reaction has been to shed geopolitical premium, a vigilant approach to monitoring both supply-side fundamentals and the delicate geopolitical balance remains paramount for sound investment decisions in the oil and gas sector.

