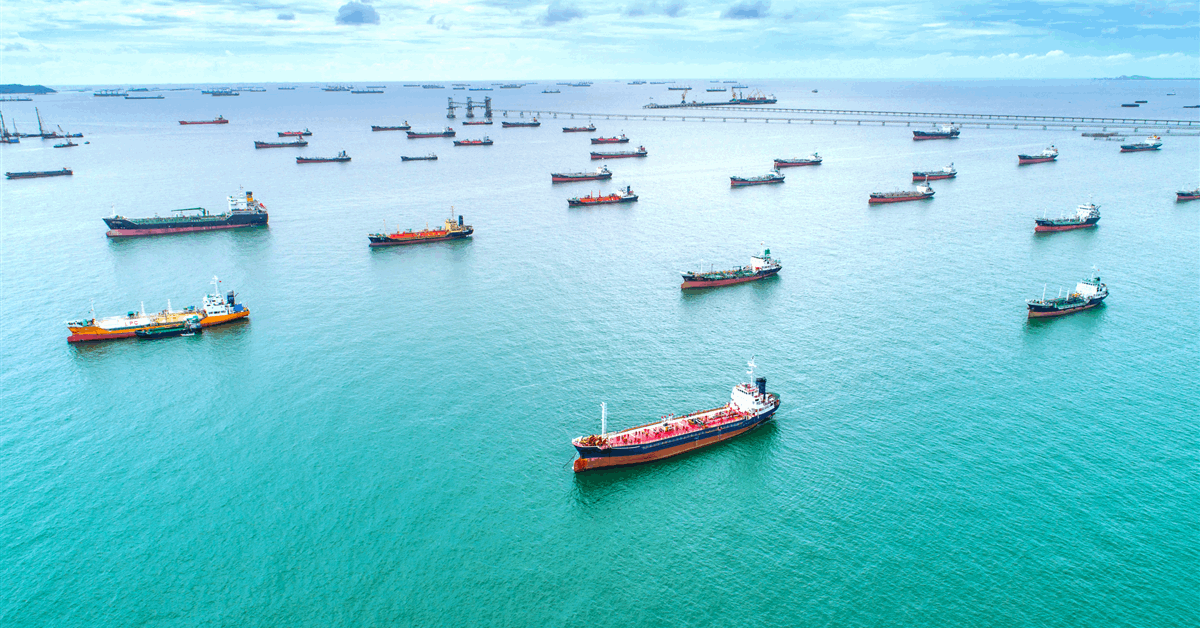
The global oil market is signaling a clear shift towards oversupply, with a critical indicator — the volume of crude oil stored on the world’s oceans — expanding to an unprecedented level. Our proprietary tracking data confirms a flotilla of 1.24 billion barrels of crude and condensate was in transit on tankers as of the week ending October 17th, marking a significant increase from 1.22 billion barrels just a week prior. This swelling maritime inventory is more than just a logistical update; it serves as a potent, real-time barometer of the widening gap between global oil supply and demand, pointing towards a decidedly bearish outlook for crude prices in the near term.
The Expanding Sea-Based Inventory: A Tangible Surplus
The record volume of crude oil navigating the world’s oceans is a direct consequence of a multi-faceted supply surge meeting a decelerating demand environment. This isn’t merely an uptick; it’s a structural build-up. A significant portion of this increase stems from key producers, both within and outside the OPEC+ alliance, stepping up their output. Simultaneously, the logistical challenges of longer voyages to deliver these barrels to end-users in Asia, primarily China, mean more oil spends more time at sea, exacerbating the visible surplus. This phenomenon is a stark illustration of the long-anticipated market surplus finally materializing, creating downward pressure on crude benchmarks as traders price in the excess supply.
Production Boom Meets Faltering Demand Growth
The current market dynamics are fundamentally driven by robust production increases that are outstripping global demand growth. OPEC+ members have been actively unwinding previous output cuts, with the group collectively raising its production target by nearly 2.5 million barrels a day between March and September. While actual production increases have slightly lagged targets, the group still added over 2 million barrels a day to global supply during this period. Notably, Saudi Arabia, the United Arab Emirates, and Russia alone have boosted their combined output by an impressive 1.77 million barrels a day. September witnessed the largest month-on-month addition in four years, with OPEC+ output rising by 630,000 barrels a day.
Beyond OPEC+, non-member nations, particularly in the Americas, are contributing significantly to this supply glut. The United States has hit new production highs, topping 13.63 million barrels a day in recent weekly data. Meanwhile, Guyana has emerged as a new player, shipping its first cargo of the Golden Arrowhead grade at the end of August, with production soon expected to plateau at 250,000 barrels a day. These newly added barrels, often traveling extended distances to reach Asian buyers, further amplify the amount of oil in transit. This surge in supply arrives precisely when demand growth is slowing, leading forecasters to project a market surplus that could escalate to as much as 4 million barrels a day in the early months of next year – a truly substantial overhang.
Market Reaction and Investor Sentiment Amidst Price Volatility
The tangible evidence of a deepening surplus is already translating into significant market volatility and a pronounced bearish trend. As of today, Brent Crude trades at $90.38, marking a sharp 9.07% decline within the day, having ranged from $86.08 to $98.97. Similarly, WTI Crude stands at $82.59, down 9.41%, with its daily range spanning $78.97 to $90.34. This recent price action is not an isolated event; our proprietary data reveals Brent’s value has plummeted from $112.78 on March 30th to its current $90.38 – a staggering $22.4 or 19.9% decline in just over two weeks. This rapid depreciation underscores the market’s immediate reaction to the expanding surplus narrative.
Our first-party reader intent data highlights the mounting concerns among investors navigating this volatile environment. Questions like “What do you predict the price of oil per barrel will be by end of 2026?” reflect a deep anxiety about future oil price trajectory, directly influenced by the current supply dynamics and projected surpluses. Investors are also keenly interested in “What are OPEC+ current production quotas?”, seeking clarity on the group’s official stance versus actual production increases. While quotas are set, the actual unwinding of cuts by key members is the primary driver of the current supply influx. The performance of individual energy companies, as seen in queries about Repsol, further illustrates how these macro trends directly impact portfolio decisions and sentiment within the energy sector. The current market conditions demand a strategic re-evaluation of investment theses, with a strong emphasis on risk management and understanding the nuances of global supply-demand fundamentals.
Navigating the Future: Key Events on the Horizon
For investors focused on the oil and gas sector, the coming weeks are pivotal, offering critical data points and potential policy shifts that could influence market direction. The most immediate and impactful events are the upcoming OPEC+ JMMC Meeting on April 19th, followed by the OPEC+ Ministerial Meeting on April 20th. These gatherings will be closely scrutinized for any indication of a change in strategy by the alliance. Given the expanding surplus and the recent sharp decline in prices, the pressure on OPEC+ to address the oversupply situation will be immense. Any decision, or lack thereof, regarding production levels will send powerful signals to the market and significantly impact crude oil prices.
Beyond OPEC+, investors must monitor weekly inventory and production data from the United States. The API Weekly Crude Inventory reports on April 21st and April 28th, followed by the official EIA Weekly Petroleum Status Reports on April 22nd and April 29th, will provide crucial insights into US crude stocks and domestic production trends. With US output already at new highs, sustained inventory builds would further reinforce the bearish outlook. Additionally, the Baker Hughes Rig Count on April 24th and May 1st offers a forward-looking indicator of drilling activity, though its immediate impact on current supply is less direct than inventory data. Collectively, these upcoming events provide essential opportunities for investors to assess the evolving supply-demand landscape and anticipate potential market reactions, guiding their strategic decisions in a rapidly changing oil market.