The Unprecedented Scale of Disruption and Current Market Reality
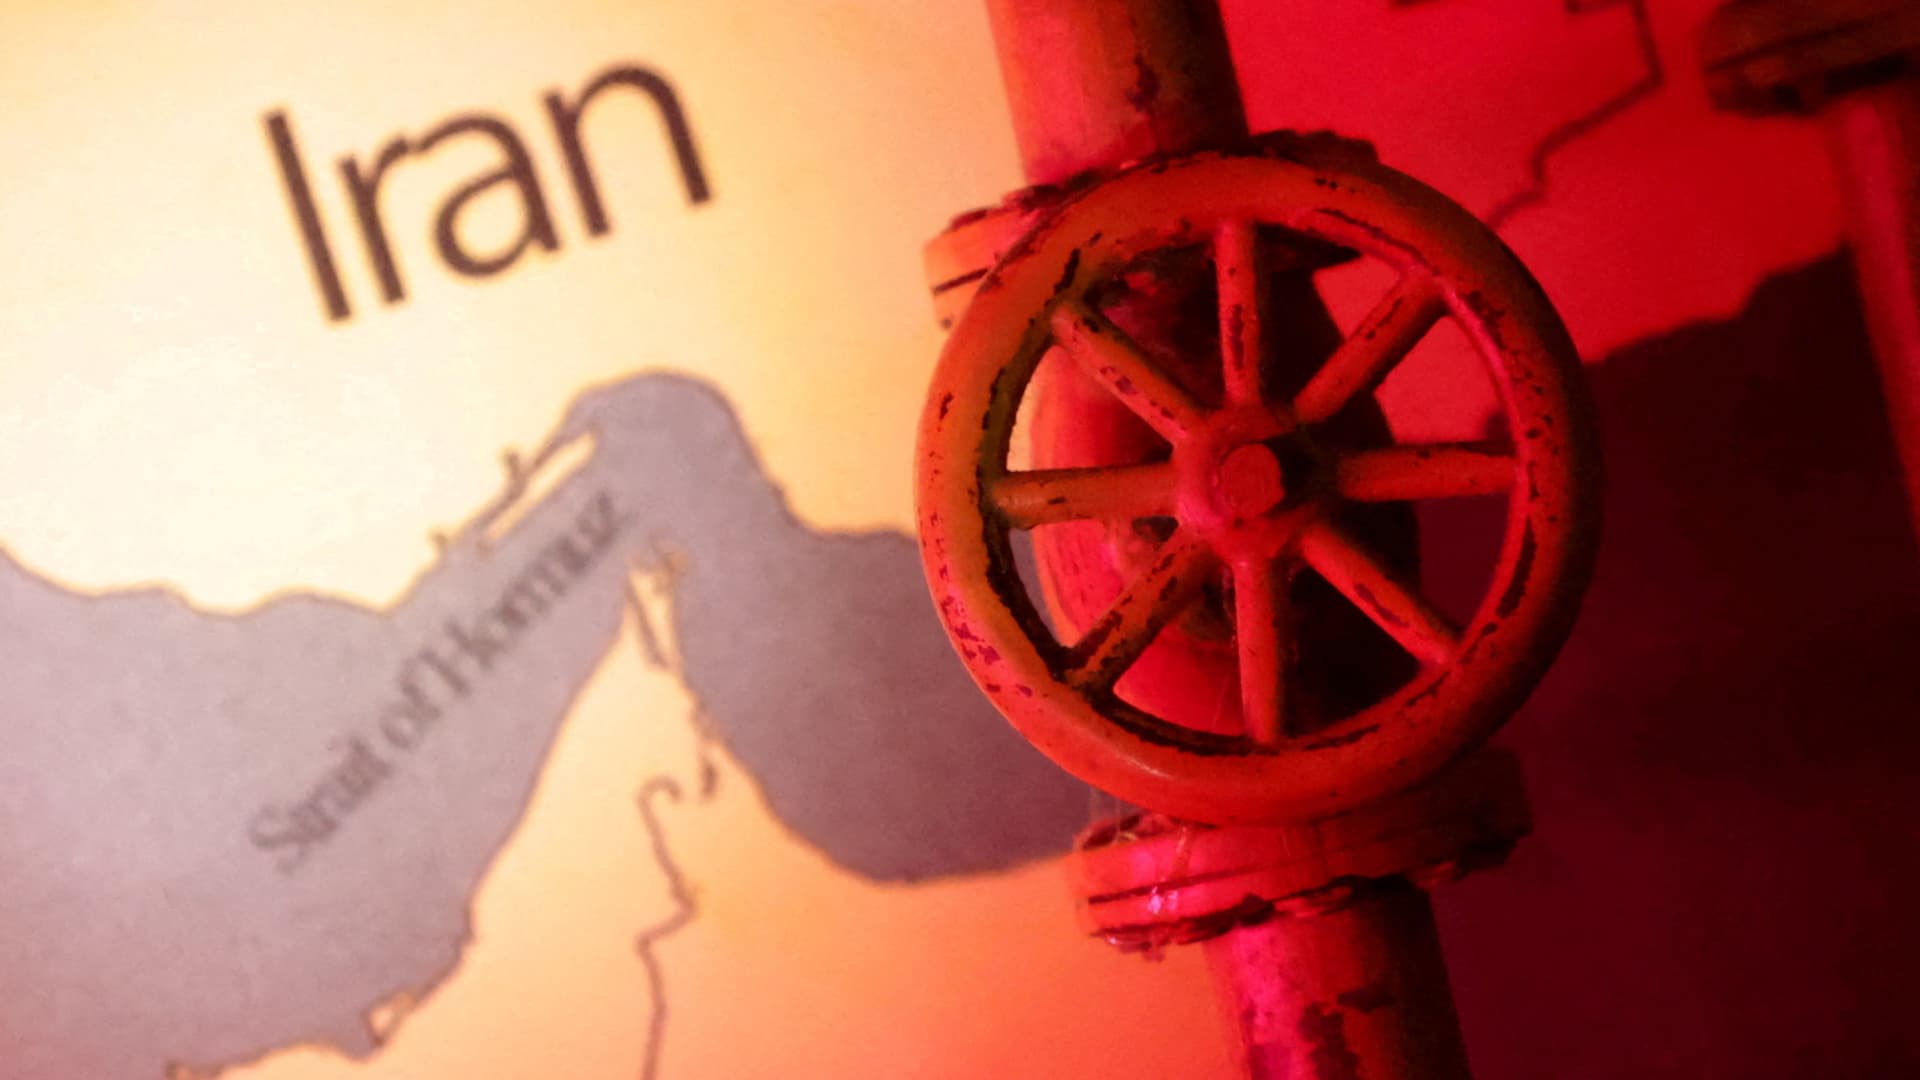
The global oil market is grappling with a supply shock of historic proportions, stemming from the US-Iran conflict and the subsequent standstill of tanker traffic through the Strait of Hormuz. For nine days now, approximately 20% of the world’s total oil supply has been disrupted, an event that dwarfs all previous crises. To put this into perspective, this disruption is more than double the impact of the 1956 Suez Crisis, which saw 10% of global supply taken offline, and nearly triple the 1973 Arab Oil Embargo’s 7% hit. The sheer volume of oil affected, coupled with the strategic choke point of Hormuz, has created an unparalleled challenge for global energy security.
While the initial news of this conflict sent crude prices surging well above $100 per barrel, reflecting immediate panic and supply concerns, our proprietary data reveals a more nuanced picture in the immediate term. As of today, Brent crude trades at $92.61, marking a 0.68% decline for the day, with its range fluctuating between $92.57 and $94.21. Similarly, WTI crude is at $89.26, down 0.46%, having traded between $88.76 and $90.71. This represents a significant retreat from the $101.16 peak observed at the beginning of April, with Brent having declined by over 7% in the past two weeks alone. This current market behavior, where prices have softened despite the ongoing, severe disruption, suggests that investors are actively weighing not just the physical supply loss but also the potential for demand destruction, the efficacy of strategic reserve releases, and the broader geopolitical outlook. The market’s initial knee-jerk reaction has given way to a more complex calculus, indicating a battle between acute supply concerns and other mitigating factors or expectations.
The Critical Absence of Spare Capacity and Its Market Implications
What truly differentiates the current crisis from historical disruptions is the critical absence of meaningful spare oil production capacity globally. In past events, such as the Suez Crisis, significant spare capacity, notably from the U.S. and parts of the Gulf, was available to cushion the blow. Today, the world holds virtually no immediate swing capacity that can be brought online to offset a 20% global supply loss. Compounding this issue, the very nations that typically hold the overwhelming majority of this capacity – Saudi Arabia and the United Arab Emirates – are themselves cut off from the global market due to the Strait of Hormuz closure. This creates a market environment with no “swing producer” positioned to step in and stabilize prices.
In a market devoid of a supply cushion, the primary mechanism for rebalancing becomes demand destruction, driven by sharply rising oil prices. This scenario forces consumers and industries to curb energy consumption, ultimately bringing demand in line with the constrained supply. While strategic petroleum reserves (SPR) offer a temporary reprieve, they are finite and insufficient to fully offset such a massive and prolonged disruption. The U.S. Strategic Petroleum Reserve currently holds 415 million barrels, approximately 58% of its total authorized capacity of 714 million barrels. While a significant volume, this is a short-term solution for a long-term problem. The pressure is mounting on International Energy Agency (IEA) member states to coordinate a joint release of these strategic stocks, an option reportedly under discussion by G7 finance ministers. However, even a coordinated release would only buy time, not fundamentally resolve the underlying supply deficit caused by the Hormuz closure.
Navigating Volatility: Investor Concerns and Forward-Looking Drivers
Our proprietary reader intent data reveals a clear sentiment among investors: uncertainty regarding price direction. Questions like “is wti going up or down” and “what do you predict the price of oil per barrel will be by end of 2026?” underscore the pressing need for clarity in a highly volatile environment. While the immediate supply shock is undeniable, the longer-term trajectory of oil prices will hinge on a complex interplay of geopolitical developments, the duration of the Hormuz closure, and the effectiveness of global policy responses.
For investors seeking to navigate this unprecedented period, monitoring key upcoming energy events will be crucial. The release of the EIA Weekly Petroleum Status Report, scheduled for Wednesday, April 22nd, and again on April 29th and May 6th, will provide critical insights into U.S. crude inventories, refinery activity, and product demand. These reports will offer early indications of whether demand destruction is beginning to manifest or if inventory draws are accelerating under the current crisis. Similarly, the API Weekly Crude Inventory reports on April 28th and May 5th will offer another data point. The Baker Hughes Rig Count, due on April 24th and May 1st, will give a glimpse into North American drilling activity, though any significant supply response from increased drilling would take months to materialize and cannot address the immediate, acute deficit. Perhaps most critically, the EIA Short-Term Energy Outlook on Saturday, May 2nd, will provide updated forecasts and assessments from a leading authority, which could significantly influence market sentiment and price expectations for the coming months and potentially into the end of 2026. Investors should pay close attention to how these reports reflect the market’s attempt to rebalance in the face of such a severe and sustained supply shock.
The current market landscape is characterized by extreme uncertainty and potential for rapid price swings. While the initial surge above $100 has seen some correction, the underlying fundamentals of a massive supply disruption coupled with zero spare capacity remain. Investors must brace for continued volatility and meticulously analyze upcoming data releases and geopolitical developments to position themselves effectively in this truly historic period for the oil market.