The US Anti-ESG Push: A New Geopolitical Layer for Oil & Gas Investors Amidst Volatility
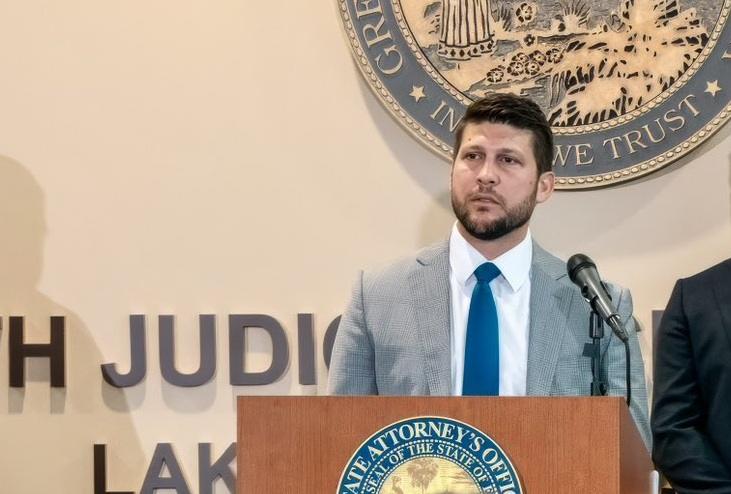
The global energy landscape is currently a complex tapestry of market volatility and deepening regulatory divergence. As of today, Brent crude trades at $90.38, reflecting a significant 9.07% decline, while WTI sits at $82.59, down 9.41%. This sharp correction from recent highs, visible in the 14-day Brent trend from $112.78 to its current level, underscores the inherent unpredictability of commodity markets. Adding another intricate layer to this environment, a coalition of 16 U.S. State Attorneys General has issued a stark warning to major tech companies like Microsoft, Google, and Meta, urging them to reject compliance with the European Union’s new Corporate Sustainability Reporting Directive (CSRD) and Corporate Sustainability Due Diligence Directive (CSDDD). This aggressive stance signals a hardening anti-ESG front in the United States, creating a critical fault line in global regulatory standards that oil and gas investors cannot afford to ignore. While directly targeting tech, the underlying legal and political philosophy behind this push has profound implications for capital allocation, operational strategy, and long-term risk assessment across all energy sectors.
The Intensifying US Stance Against ESG Mandates and its Energy Echoes
The letters from the State Attorneys General represent a significant escalation in the domestic pushback against environmental, social, and governance (ESG) mandates. They explicitly warn that compliance with the EU’s detailed sustainability reporting and due diligence requirements could expose American companies to “lawsuits and government enforcement actions” under U.S. law, including deceptive trade practice and antitrust issues. The AGs argue that these EU directives compel American companies to adopt European ESG and Diversity, Equity, and Inclusion (DEI) standards, which they deem “unlawful in the United States.” This isn’t just about specific tech companies; it’s a clear signal that a powerful political bloc in the US views aggressive ESG implementation as potentially conflicting with national interests and existing legal frameworks. For oil and gas investors, this translates into a potentially less burdensome domestic regulatory environment regarding sustainability reporting, contrasting sharply with the increasingly stringent requirements faced by European counterparts. This divergence could influence investment flows, favoring regions with perceived lower compliance costs and less pressure for rapid energy transition, at least in the short to medium term.
Navigating the Regulatory Chasm: Risks and Opportunities for Global Energy Players
The explicit warning from US Attorneys General creates a significant dilemma for multinational energy companies with operations spanning both sides of the Atlantic. The EU’s CSRD and CSDDD impose extensive obligations, from identifying impacts on human rights and the environment to reporting on sustainability-related risks. The US position, however, frames compliance with these very directives as a legal liability. This regulatory chasm forces global energy players to carefully reassess their compliance strategies, potentially leading to segregated reporting frameworks or a cautious approach to sustainability initiatives that could be perceived as aligning too closely with EU mandates. The ambiguity inherent in “unascertainable reporting requirements” cited by the AGs introduces a new layer of legal and operational risk. For investors eyeing global energy majors, understanding how these companies plan to navigate these conflicting demands will be crucial for assessing their risk profiles and long-term strategic resilience. Companies like Repsol, which readers have inquired about, operating in diverse global markets, will need robust strategies to manage these diverging pressures effectively, impacting their capital expenditure decisions and sustainability roadmaps.
Crude Volatility Amidst Policy Headwinds: What Our Data Reveals
Against this backdrop of policy uncertainty, crude markets are showing significant short-term volatility. As of today, Brent crude trades at $90.38, reflecting a significant 9.07% decline, while WTI sits at $82.59, down 9.41%. Gasoline prices have also seen a substantial drop, now at $2.93, a 5.18% decrease. This downward pressure comes even as the geopolitical landscape remains tense in some regions. Looking forward, our proprietary event calendar highlights critical upcoming catalysts. The OPEC+ Joint Ministerial Monitoring Committee (JMMC) and the full OPEC+ Ministerial Meeting are scheduled for April 19th and 20th. These meetings are pivotal; any decisions on production quotas will directly impact global supply and prices. Investors are particularly keen on understanding “what are OPEC+ current production quotas?” and how global demand signals, including those influenced by regulatory environments, might sway their strategy. Further insights into supply-demand dynamics will come from the API Weekly Crude Inventory (April 21st, 28th) and the EIA Weekly Petroleum Status Report (April 22nd, 29th), while the Baker Hughes Rig Count (April 24th, May 1st) will offer a glimpse into North American drilling activity. The confluence of a volatile market and a deepening regulatory divide between major economic blocs adds another layer of complexity to these traditional supply-side considerations.
Investor Focus: 2026 Outlook and Shifting Capital Flows
The intensifying US anti-ESG movement has direct implications for long-term investment strategies in oil and gas. Many investors are keenly focused on the 2026 outlook, with questions like “what do you predict the price of oil per barrel will be by end of 2026?” dominating our inquiries. The answer, in part, will depend on how this regulatory divergence influences capital flows. If US-based energy companies face less pressure to de-carbonize rapidly or divest from fossil fuel assets due to a robust anti-ESG environment, it could encourage continued investment in traditional exploration and production. This might lead to a more stable or even increased supply from North America, potentially tempering price spikes in the long run. Conversely, companies operating primarily in the EU will continue to face immense pressure to meet stringent sustainability targets, influencing their capital expenditure towards green energy projects. This creates a fascinating dynamic: a two-speed energy transition where investment decisions are increasingly shaped by jurisdiction-specific political and regulatory climates rather than a unified global ESG agenda. Investors must carefully assess the geographical exposure of their energy portfolios and the strategic agility of management teams in navigating this increasingly fractured global regulatory environment.