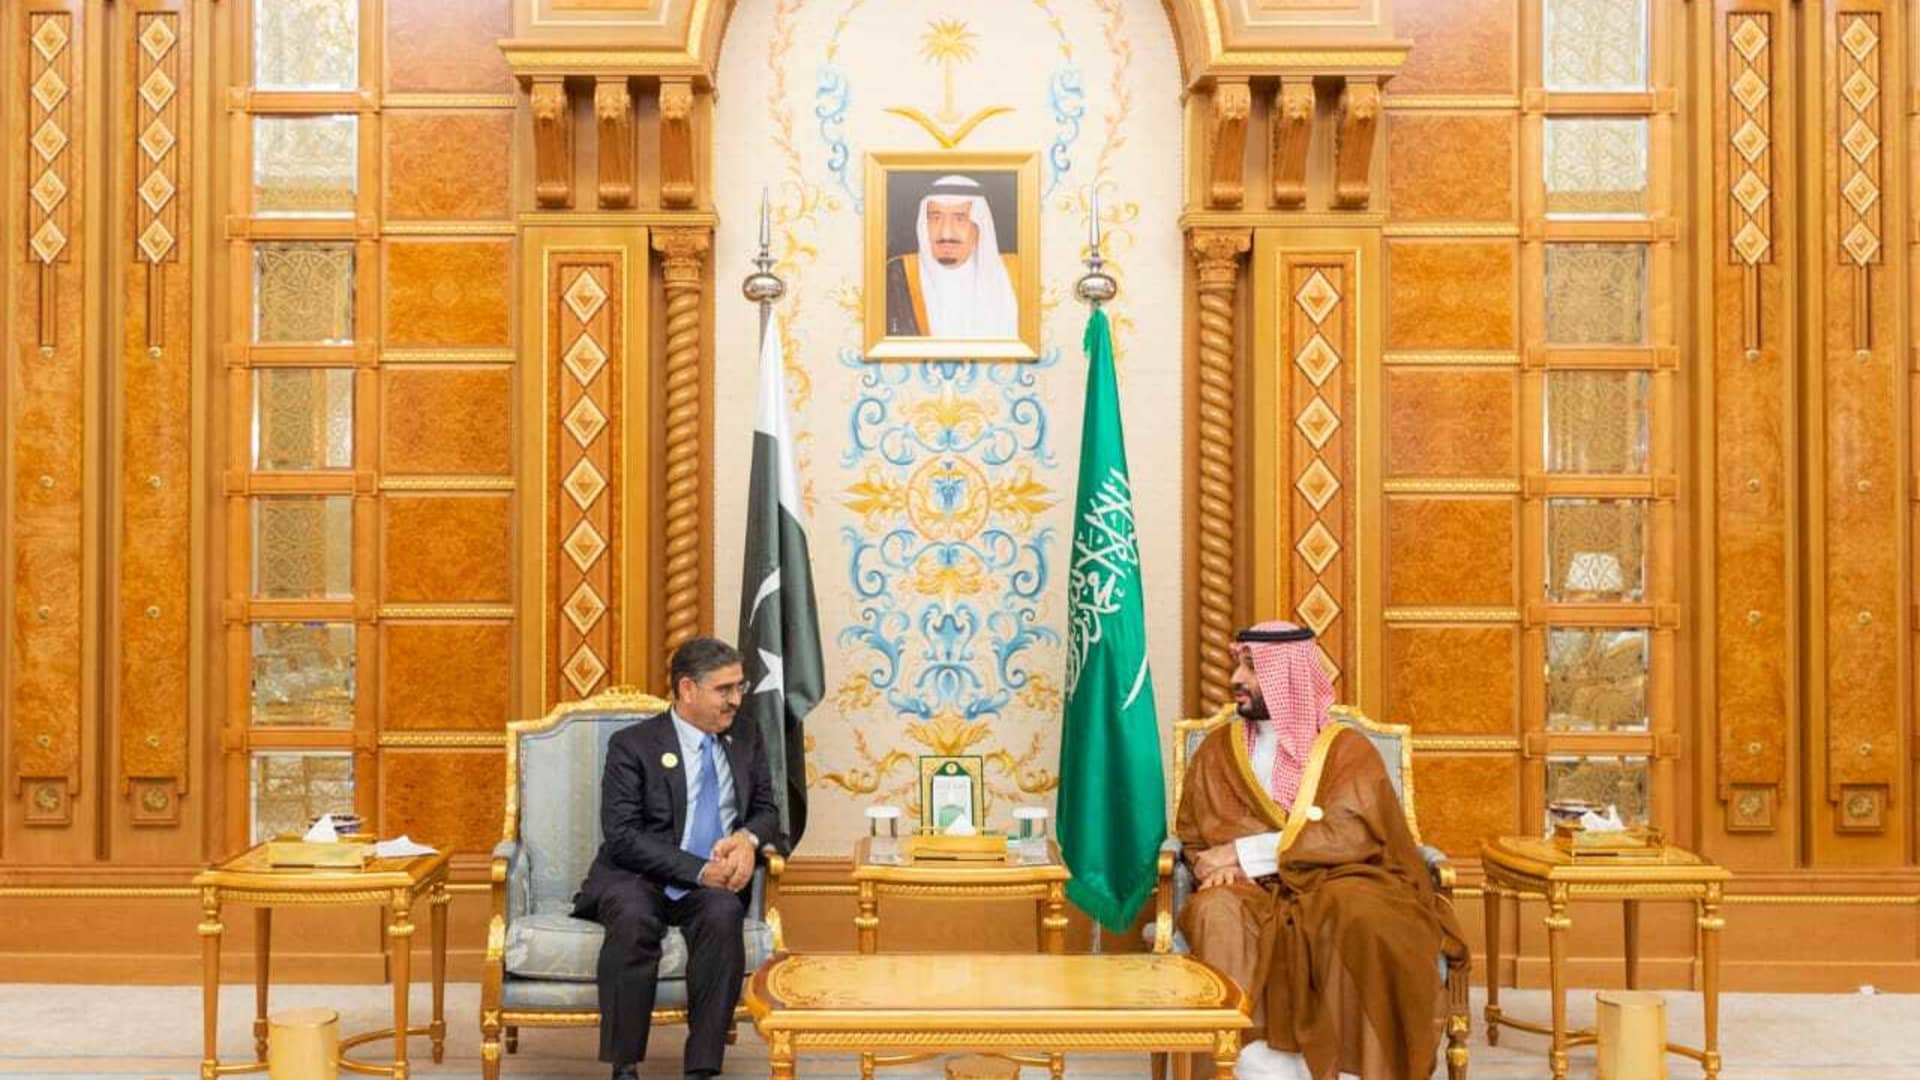
The global oil market is a complex web of geopolitical alliances, economic imperatives, and fundamental supply-demand dynamics. Recent developments, such as the mutual defense pact between Saudi Arabia and Pakistan, naturally prompt investors to question the stability of established energy trade relationships. Our analysis indicates that while Riyadh is actively broadening its security alliances, these strategic shifts are unlikely to disrupt its crucial commercial energy ties, especially with a key consumer like India. For oil and gas investors, understanding this distinction between geopolitical posturing and enduring commercial logic is paramount to navigating the market’s inherent volatility.
Geopolitical Alignment vs. Enduring Commercial Flows
The recently formalized mutual defense pact between Saudi Arabia and Pakistan has garnered attention, particularly given India’s long-standing geopolitical tensions with its neighbor. However, proprietary intelligence from our network suggests that this agreement will not alter the fundamental energy relationship between Saudi Arabia and India. Saudi Arabia remains steadfast in its commitment to commercial ties, recognizing India as one of the world’s largest crude consumers and a critical customer. In July alone, Saudi Arabia supplied over 600,000 barrels per day to India, placing it firmly among India’s top three crude suppliers alongside Russia and Iraq.
This commitment underscores a broader trend: while Gulf states, including Saudi Arabia, are indeed exploring diversified security partnerships in response to evolving regional dynamics and perceived shifts in traditional alliances, these efforts are not coming at the expense of their core economic interests. India’s Ministry of External Affairs has acknowledged the development, stating its intent to “study the implications,” but the consensus among industry insiders points to the continued security of oil flows. For investors, this signals stability in a key demand corridor, mitigating concerns that geopolitical realignments might trigger supply disruptions or trade re-routes from a major producing nation to a major consumer.
Market Realities and the Unwavering Dollar Standard
In a dynamic market environment, investors are consistently seeking clarity on price direction and the stability of underlying financial mechanisms. Many of our readers are asking about the current Brent crude price and the models powering our real-time data. As of today, Brent crude trades at $98.22, reflecting a 1.18% decline for the session, with a daily range between $97.92 and $98.67. This marks a notable shift from just two weeks ago, when Brent stood at $112.57, representing a significant 12.4% retracement over the past 14 days. Meanwhile, WTI crude similarly saw a 1.62% dip, settling at $89.69, within its daily band of $89.50-$90.26. This recent downward pressure reflects a combination of factors, including broader macroeconomic concerns and the anticipation surrounding upcoming supply-side decisions.
Beyond daily price fluctuations, another frequently discussed topic among investors is the long-running speculation about a potential shift away from the U.S. dollar for Saudi oil trade. Our analysis, informed by high-level contacts, firmly dismisses these rumors as a “phantom agreement.” Dollar pricing remains the immutable foundation of Saudi crude exports. This commitment to the greenback provides crucial stability and liquidity to the global oil market, reassuring investors that despite Riyadh’s complex balancing act of security ties with nations like the U.S. and Pakistan, and expanding energy trade with BRICS member India, the core financial architecture of crude transactions remains firmly in place. This steadfastness is a critical anchor for global energy investment, minimizing currency-related risks in major oil trades.
India’s Strategic Energy Security and Investor Focus
India’s position as a burgeoning economic power and a leading crude importer makes its energy strategy a focal point for global oil investors. The nation’s decades-long conflict with Pakistan might suggest vulnerability in its supply chains when Saudi Arabia deepens ties with Islamabad. However, India’s strategic approach to energy security is robust and diversified. Its relationships with top suppliers like Saudi Arabia, Russia, and Iraq are built on commercial merit and mutual interest. As one expert noted, “it’s in their interest” for Saudi Arabia to maintain its strong commercial relationship with India, irrespective of other alliances. This perspective is vital for investors to grasp: national interests, particularly economic ones, often transcend geopolitical friction when it comes to vital commodities like oil.
Furthermore, India’s proactive engagement in forums like BRICS highlights its intent to forge multi-faceted partnerships, ensuring a resilient energy supply matrix. Investors should interpret India’s “awareness” and “study” of the Saudi-Pakistan pact not as a sign of immediate concern for oil flows, but as a standard diplomatic response. The underlying commercial and strategic rationale for Saudi Arabia to maintain its supply to India remains powerful, driven by India’s immense demand growth and its pivotal role in global energy consumption patterns. This stability in a critical demand center offers a degree of predictability for long-term oil market outlooks.
Upcoming Catalysts: Navigating Future Price Action
For investors actively engaged in the oil and gas sector, understanding the calendar of upcoming events is crucial for positioning and risk management. Many of our readers are keenly interested in “What are OPEC+ current production quotas?” and the broader impact of their decisions. The immediate spotlight falls on the OPEC+ Joint Ministerial Monitoring Committee (JMMC) meeting scheduled for tomorrow, April 17th, followed by the full Ministerial meeting on April 18th. These gatherings are pivotal, as they will determine any potential adjustments to production policies that could significantly influence crude prices and market sentiment in the near term.
Beyond OPEC+, a steady stream of vital data points will continue to shape the market narrative. The API Weekly Crude Inventory report on April 21st, followed by the official EIA Weekly Petroleum Status Report on April 22nd, will provide critical insights into U.S. supply and demand dynamics, including inventory levels, refinery activity, and import/export figures. These reports often trigger immediate price reactions. Further out, the Baker Hughes Rig Count on April 24th and May 1st will offer a forward-looking indicator of drilling activity and potential future supply. Investors must closely monitor these events, as they represent the most significant short-term catalysts for price volatility and provide essential data for assessing the fundamental health of the global oil market.

