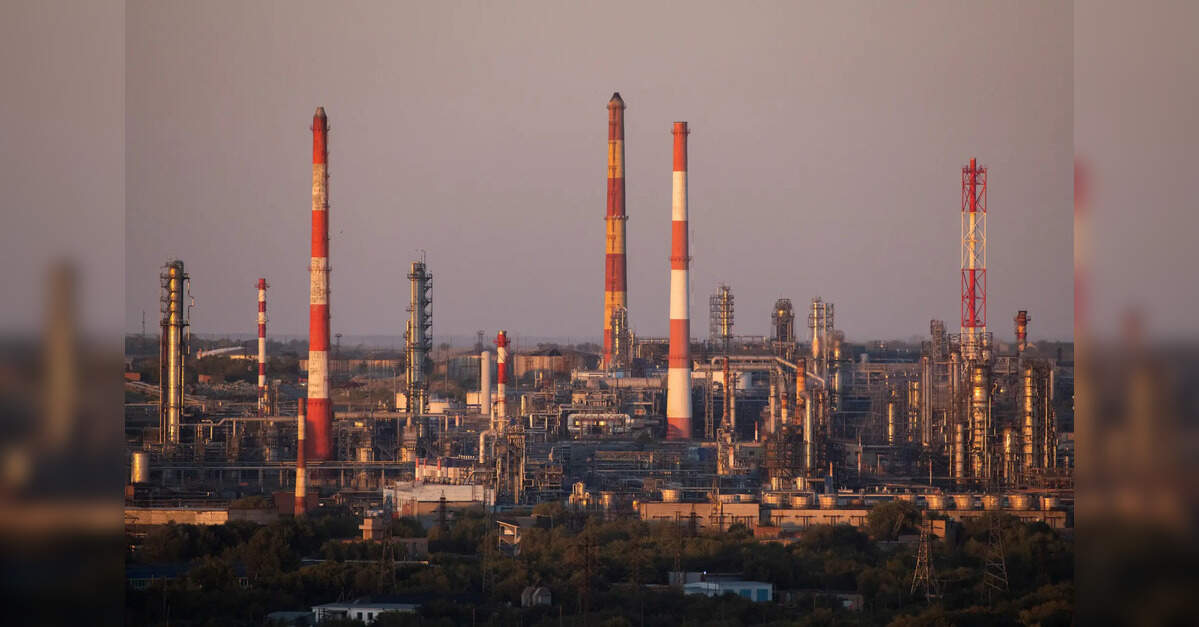
The global oil and gas investment landscape is abuzz with the impending bids for Chevron’s significant 50% stake in Singapore’s second-largest refinery. This strategic asset, with a robust crude processing capacity of 290,000 barrels per day, has attracted the keen interest of commodity trading giants Vitol and Glencore. Their anticipated formal bids, expected by October, underscore the intense competition and strategic importance of refining capabilities within the Asia-Pacific region, a critical hub for global energy trade.
The Strategic Imperative of Asia-Pacific Refining Assets
Singapore stands as an undeniable cornerstone of the global oil market, serving as Asia’s largest oil trading hub and the world’s premier bunkering port. This makes a refining asset of 290,000 barrels per day capacity, like the one on Jurong Island, exceptionally valuable for players seeking to enhance their regional influence and optimize trade flows. Vitol and Glencore, both with established refining footprints in the Asia-Pacific, view this acquisition as a direct pathway to expanding their asset base and bolstering trade volumes. Vitol already operates a 32,000 bpd refinery in Malaysia and holds a 50% stake in the ATB Oil terminal, alongside its Viva Energy operations in Australia which include the 120,000 bpd Geelong refinery. Glencore, through its joint venture with Chandra Asri, also has a significant presence via Aster Chemicals and Energy in Singapore, operating a 237,000 bpd refinery and chemical complex. The estimated $1 billion valuation for the entire refinery highlights the substantial investment required, signaling the long-term confidence these firms place in the region’s energy demand. A crucial aspect of this transaction is the existing 50% ownership by Chinese state oil giant PetroChina, which holds a first right of refusal, adding a layer of strategic complexity to the bidding process.
Chevron’s Divestment Strategy Amidst Market Volatility
Chevron’s decision to divest its stake is part of a broader, aggressive strategy to cut up to $3 billion in costs by the end of 2026. This portfolio optimization extends beyond the Singapore refinery, encompassing other Asian assets such as terminal and fuel storage facilities in Australia and the Philippines, and retail stations in Malaysia, which could be offered as a bundled package or separately. This strategic repositioning is occurring against a backdrop of fluctuating crude prices, which directly impact the profitability of refining operations and the valuation of such assets. As of today, Brent crude trades at $98.15 per barrel, reflecting a 1.25% decrease, while WTI crude is at $89.8 per barrel, down 1.5%. This current snapshot follows a notable trend over the past 14 days, where Brent crude prices experienced a significant $14 decline, or 12.4%, falling from $112.57 to $98.57. Such volatility can create both challenges and opportunities for divestment and acquisition. While a softening crude market might compress initial sale valuations, it could also signal an opportune moment for buyers like Vitol and Glencore to secure a major asset if they anticipate a rebound in refining margins or a long-term increase in regional product demand.
Navigating Future Market Dynamics: What Investors Are Asking
Investors closely monitoring this high-stakes deal are keenly focused on the broader macro-economic and supply-side factors that will shape the profitability of such an acquisition. Our proprietary reader intent data reveals a consistent demand for clarity on key market drivers, with frequent inquiries such as “What are OPEC+ current production quotas?” and “What is the current Brent crude price?” These questions are not merely academic; they underscore the direct link between global crude supply policies, benchmark prices, and the ultimate financial performance of refining assets. The timing of final binding bids in October means that bidders, and by extension, investors, must project future oil market conditions, including feedstock costs and refined product demand in a dynamic Asia-Pacific market. Clarity on OPEC+ decisions provides a critical input for forecasting crude availability and price stability, while real-time Brent prices offer an immediate gauge of market sentiment and refining margin potential. Investors are seeking robust data and analysis to inform their understanding of the risks and rewards inherent in a major refining acquisition, especially one situated in a pivotal global trading hub.
Upcoming Events and the Road to Final Bids
The road to Chevron receiving final binding bids in October is paved with several critical energy market events that will undoubtedly influence the strategic calculus of Vitol, Glencore, and potentially PetroChina. The immediate focus turns to the upcoming OPEC+ Joint Ministerial Monitoring Committee (JMMC) meeting on April 17th, followed by the Full Ministerial meeting on April 18th. Any shifts in production quotas announced at these gatherings could significantly impact crude supply and price forecasts for the remainder of the year. Following these, the market will scrutinize the API Weekly Crude Inventory reports on April 21st and 28th, along with the EIA Weekly Petroleum Status Reports on April 22nd and 29th, for vital clues on U.S. demand and supply balances. These inventory figures often serve as a bellwether for global oil demand sentiment. Furthermore, the Baker Hughes Rig Count on April 24th and May 1st will provide insights into future drilling activity and potential crude supply trends. Collectively, these events create a dynamic environment where the perceived value and future profitability of the Singapore refinery could shift. Savvy investors will be closely watching these developments, understanding that each data point contributes to the complex valuation models used by the bidding parties to finalize their offers for this crucial Asia-Pacific asset.


